Home

Who Should Consider Business Development Coaching for Their Exit Planning Practice?

If you lead an exit planning practice and want to grow, get better, or reach new goals, you should consider business development coaching. Owners experiencing slow growth, having trouble reaching new clients, or unsure how to craft a plan can receive real benefit from this assistance. Professionals new to exit planning or those who want to build repeatable steps fit well for coaching. Teams who need smarter ways to communicate with clients or arrange deals will see coaching create a noticeable impact. Even firms with decades of work can get blind spots and a fresh perspective. To discuss who should consider business development coaching for their exit planning practice and how coaching works, below we outline some important points and options for exit planning leaders.

Key Takeaways

  • Business development coaching is essential for exit planning advisors facing stagnant growth, high workloads, ambitious scaling goals, or those new to the practice. It offers tailored guidance for each scenario.
  • Implementing coaching can revitalize practices by introducing innovative strategies, structured methodologies, and continuous learning. This leads to enhanced business sustainability and client satisfaction.
  • Coaching helps advisors create actionable frameworks, efficient workflows, and accountability systems, making meaningful progress feel inevitable and measurable.
  • Certified exit planning advisors should consider business development coaching to enhance their exit planning practice.
  • How to select the right coach Picking the right business development coach for your exit planning practice is an important decision. Here are a few tips on conducting your due diligence.
  • To get the most from coaching investment, business development coaches should identify specific goals, commit 100% to the process, and actively integrate feedback, creating a virtuous cycle of constant improvement and sustained success.
Corporate Training for Financial Advisory Firms

Who Needs Coaching?

Business development coaching isn’t for everyone. Who Needs Coaching? Not everyone should get coaching in exit planning. Knowing what these profiles look like will help clear up who needs coaching for their exit planning practice. Here, we demystify the five types of people who can benefit most from coaching.

The Stagnant Practice

Established tradition that has experienced minimal expansion likely requires a new viewpoint. If a business is more than 10 years old but has no exit plan, you’re stuck. To do so, begin with a deep dive into current performance measures. Think about monthly sales growth, client retention, and service adoption. You need creative approaches, whether it’s introducing new service lines or refining your onboarding systems to shorten client ramp-up times. To break through barriers, you need a plan of attack that includes regular check-ins to measure your progress and pivot as markets shift. It’s a great way for seasoned owners to keep pace in a fast-evolving landscape.

The Overwhelmed Advisor

Advisors overwhelmed by client demands and administrative obligations can forget what you’re trying to accomplish. It can really help to build systems that automate the banal work, such as digital onboarding or workflow tracking. Whether it’s prioritizing tasks by zeroing in on high-value relationships or strategizing, this approach lets stressed advisors take back control. Time management techniques, such as batching like tasks or capping meeting times, provide an additional surge of efficiency. In a coaching environment that supports open discussion of challenges, advisors can learn from their peers and discover real-world solutions.

The Ambitious Scaler

Who needs coaching? Establishing growth targets, such as increasing your client base by 20% in a year, provides focus. Strategic partnerships, teaming with other specialists or leveraging cross-border expertise, can assist in scaling more quickly. Smart marketing, such as targeted messaging on the value of exit planning, attracts new clients. You can invest in professional development, perhaps through leadership workshops to make sure the team is prepared for expansion.

The New Practitioner

New exit planners need solid roots. You need training in best practices and industry standards. You need to connect with mentors who have made transitions before. Cultivating a network of professional groups provides learning and growth. Access to actionable resources, such as planning sheets or checklists, allows budding practitioners to get over initial frustrations and start gaining confidence.

The Succession Planner

Succession planning is tricky and emotional. We guide you through defining the critical pieces of your plan, like financial structures and transition timelines, so you don’t overlook anything. By involving successors, be they family or management, you get buy-in. Considering the economic implications and timing critical milestones keeps the plan grounded. Coaching three years prior to a transition is perfect for a clean handoff.

Why Consider Coaching?

Business development coaching for exit planning isn’t simply about ramping up your income in the present. It expands the frame from gain to sustainable resilience. Business owners view coaching as an investment, with industry statistics reporting 89% receiving a return greater than what they paid. Coaching can disrupt old patterns, assist in redirecting your attention away from quick fixes and toward establishing a brand that people want to work with, and can provide new growth opportunities in exit planning. Coaching owners develop stronger client relationships, resulting in more return business and consistent expansion. When leaders strategize, they sidestep debt traps and tax issues, cultivate trust, and position the business to survive shifts or shocks.

Beyond Revenue

For coaching forces owners to look beyond the next big deal or the quick profit. Instead, it helps them establish a steady trusted practice that garners esteem. With a coach, leaders think about brands and not just sales figures. They figure out how to invest in long-term relationships, the kind that brings them consistent referrals and devoted clients. Strategic planning receives a boost, providing owners with a clearer roadmap to achieve financial objectives and navigate marketplace fluctuations. Coaching provides a neutral, outside perspective that simplifies the identification of risks or blind spots that might harm business.

Client Impact

Metric

Before Coaching

After Coaching

Client Satisfaction (%)

67

87

Client Retention (%)

56

81

A coach co-designs services to fit each client’s needs instead of providing a cookie-cutter service. Informal conversations with clients become routine so executives can experience the feedback and pivot rapidly. Real-world client stories can make exit planning services more trusted, illustrating how a bespoke plan created a huge impact. This makes practices popular and keeps clients returning.

Practice Value

  1. Establish a reputation for competence, security, and consistent outcomes, which includes telling authentic client achievements, establishing rigorous quality controls, and honoring commitments.
  2. Introduce new services that complement your core offering, such as succession planning and risk checks, to provide clients additional incentives to stick around.

It builds service diversity which makes your practice more robust to market fluctuations and more desirable if you exit down the road. Great coaching forces accountability, so teams hit targets and maintain excellence. With an eye toward growth down the road, big change — selling, passing the business on, rough periods — is easier to plan for.

What Coaching Involves

Business development coaching for exit planning offers a combination of education, actionable tools, and support — everything advisors and their clients need to make ownership transition a smooth process. Coaching is not a cookie cutter process. It is a blend of skill upgrades, actionable frameworks and built-in accountability, each customized to the specific context and goals of the business. It can begin anywhere from three to five years out before a desired transition, emphasizing leadership, infrastructure, and human and social capital. This philosophy addresses more than just technical knowledge. It requires a combination of disciplines and a clear actionable strategy.

Skill Blending

A quality coaching program allows advisors to develop a well-rounded skillset. Financial planning is a big portion and ensures that the eventual exit aligns with individual and company objectives. Relationship management is equally important. Advisors have to learn to collaborate with heirs, management teams, and external consultants. For instance, bootcamps commonly provide access to leadership coaches, accountants, and insurance experts.

Continuous learning is emphasized throughout. Industry trends shift and being up to date allows advisors to provide smarter advice. Coaching has a peer sharing aspect, where advisors discuss what succeeds and what fails. This closes skill gaps and builds community.

Sometimes, coaches construct custom training modules to address what they spot in a practice. Some teams may require additional help with succession planning or crisis management. Others may need to work on communication or data analysis. I want to coach each advisor to grow in a way that benefits the entire team.

Actionable Frameworks

Business development coaches typically come with trusted frameworks to guide the exit planning process. These could consist of detailed processes for phases such as discovery, planning, and execution. Templates and checklists guide advisors to initiate and monitor every phase, from business valuation to succession planning.

Frameworks need to be flexible. Different models of business and clients necessitate different things. For instance, a few owners might require greater assistance with the “5 D’s” (Divorce, Disability, Disagreement, Death, Distress) to mitigate risks. Some may require instruments for involving family or key managers as successors.

Structured methodologies simplify complex planning. Instead of piecemeal efforts, advisors can use a repeatable process. This makes it easier to evaluate progress and adjust strategies when needed.

Accountability Systems

Accountability is an essential component of good coaching. Weekly check-ins keep folks on track. Advisors convene to discuss progress, address any obstacles, and establish next steps. Performance metrics, such as hitting key time points or value targets, measure how well the process is working.

A culture of accountability means that advisors hold one another up. One pair work, peer review, and feedback sessions can be as informal as sharing wins and setbacks in a group call or as formal as quarterly performance reviews.

There is self-reflection at every turn. Advisors are requested to review what is effective, what is not, and what should change. This creates accountability and aids in maintaining a long-term vision.
Corporate Training for Financial Advisory Firms

The CEPA Coaching Edge

That’s what makes the CEPA coaching edge so compelling. It provides an exit strategy business owners can follow. It introduces a structure that centers the owner’s objectives and enterprise well-being and future. This is not a cookie-cutter framework. It bends to the needs of each owner, using thoughtful analysis of financials, markets, and business operations. Coaches assist owners in establishing timelines, identifying growth gaps, and navigating complex issues such as taxes, regulations, and family drama. CEPA coaching owners report feeling prepared and confident about what’s next. The support goes beyond the exit itself and assists owners in establishing fresh personal and work goals for life beyond the business. A network of experts’ access is integral to this, providing owners with continuous support and actionable guidance.

Activating Credentials

Let the CEPA designation be a cornerstone of your public identity as a certified exit planning advisor. Putting the credential on business cards, websites and in pitches demonstrates dedication to best practices and ethical standards. The CEPA badge is more than a label; it tells clients and peers that the advisor is trained to address complex business exits. In a saturated market, this credential differentiates advisors and establishes trust with owners seeking assurance in their pathfinder. Learning never stops; advisors should stay updated on new regulations and emerging trends to maintain their expertise and keep their credential valuable. This not only helps bring in new clients, but it comforts existing ones that their advisor is cutting edge.

Deepening Expertise

Advanced training keeps advisors at the leading edge of their field, particularly as exit planning tools and regulations evolve. Workshops and seminars are great opportunities to learn from industry leaders and share best practices. Fostering a culture where teammates discuss out loud what works—hits, misses, lessons—makes all of us better. Other advisors see benefit in choosing a niche, such as family businesses or rapidly evolving industries. This special knowledge enables them to provide more specific and personalized advice and better serve diverse clients.

Community Leverage

Networking with other exit planning advisors generates opportunities to exchange practical tips and effective tools. Meet other advisors facing the same challenges through in-person and online networking events. Teaming up on projects not only raises an advisor’s profile, it can open the door to new opportunities. The community is one to turn to for advice when deals get tough or to celebrate when a big exit goes great.

How to Select a Coach

Selecting the perfect business development coach for your exit planning practice is a high-stakes decision that defines the trajectory of your firm’s growth. You need a systematic process, considering practical and interpersonal factors, as well as the coach’s industry expertise. Thoughtful selection guarantees that the coach’s strengths complement your needs and their approach and history align with your practice’s objectives and values.

Proven Methodology

  • Review the coach’s frameworks: Are they structured with outcome-driven processes, or do they rely on unstructured and flexible approaches?
  • Examine client outcomes. Look for evidence of measurable progress, such as improved exit values, faster deal cycles, or higher client satisfaction rates.
  • Request testimonials or case studies. Analyze feedback from other exit planners who have worked with the coach.
  • Make sure the coach applies techniques specific to exit planning, not generic business advice.
  • Ask about mechanisms for tracking progress and goal achievement.

Programs with obvious measures of accomplishment, like periodic checkpoints or milestone tracking, keep you informed whether you’re progressing toward your goal. Systems are useful for those who require plans and accountability. More open methods can suit those with changing requirements.

Industry Focus

Identify a coach with hands-on experience in exit planning or related industries. You need someone who understands the unique legal, financial, and operational hurdles in this space. Inquire candidates about their experience with similar businesses and their knowledge of relevant regulations or trends.

A coach who stays current with tax law, succession, or valuation standards can identify risks and opportunities that you overlook. If a coach has led exit planning for professional services, manufacturing, or tech companies, their advice will be more nuanced and practical.

Personal Chemistry

A coaching relationship requires candor. Tests for values and communication fit in trial sessions. Match the coach’s style—direct, collaborative, reflective—to what you find motivating. Can you share sensitive information without concern?

See if the coach listens, provides candid feedback, and is accessible between visits. Trust your gut in these meetings. If it smells funny, keep shopping.

Warning Signs

Avoid coaches with flimsy credentials or no exit planning experience. Promises of rapid, outsized impact without a well-defined path are warning signs. Unanswered emails, huffing and puffing when you ask questions, or a cookie-cutter coaching approach that doesn’t keep your objectives in mind are red flags.

Maximize Your Investment

Business development coaching for exit planning only pays off if you’re involved from beginning to end. It’s not enough to attend to thrive. You make a list, you follow that list, and you take each one deliberately. A lot of owners fall behind on exit planning, particularly when the growth of the business conflicts with exit objectives. Locating just 30 minutes each day—even during hard phases such as due diligence—can push you ahead. Paying down debt not only reduces expenses, it increases earnings, which makes your business more attractive to buyers. Good records and a focus on buyer-desired features will assist you in receiving superior offers. Just make sure that tips from outsiders don’t translate into relinquishing too much control or equity.

Define Success

Begin by establishing goals that you can measure, such as increasing your net profit by 10 percent over the course of a year or reducing a certain amount of debt. Get the most from your investment. Share those objectives and be certain that you both agree on their measurement. Check your progress regularly. About: Get the most out of your investment. When you get a bullseye, pause to note the victory. This keeps you on mission and energizes the long play.

Commit Fully

You need steady effort and to carve out time for coaching. Prioritize these meetings. Write notes and then immediately put into action what you learn. Anticipate that certain changes will come across as hard. Be open to new methods, even if they defy your old routines. It makes it easier to double down on what you tell someone else you’re going to do. When you tell your objectives to peers or mentors, you’re more likely to follow through with them.

Implement Feedback

Seek feedback every session and use it to address vulnerabilities. Make advice actionable. For instance, if your coach says your cash flow tracking could use some work, then get a new report or tool in place within the week. Check the results regularly. Did your return increase since you implemented some changes? Get your team involved, too. A culture that embraces feedback will keep your company scalable and primed for your exit strategy, selling or staying on.

Conclusion

Business development coaching is ideal for advisors who desire to scale their exit planning practice with less guesswork and more actionable steps. Coaches provide honest feedback, demonstrate fresh case-solving approaches, and assist in establishing impactful goals. In markets where the pace of change is rapid, a coach’s assistance can translate to quicker victories and increased client confidence. Selecting a coach with exit planning expertise fosters strategic action and safeguards your time. Huge growth doesn’t happen by chance. It comes from hard work, powerful leverage, and the right assistance. If you want to experience bigger gains in your exit planning work, consider coaching as a genuine next step and find a coach who fits your journey.

Frequently Asked Questions

Who should consider business development coaching for exit planning?

If you’re an advisor, consultant, or exit planning professional who wants to grow your practice, achieve better client results, or is struggling with business development, coaching is for you.

How does coaching benefit exit planning professionals?

Coaching provides actionable strategies, accountability, and expert guidance. It enables professionals to connect with more clients, generate more revenue, and grow more resilient firms.

What experience should a business development coach have?

A business development coach should have proven experience in exit planning, strong coaching skills and a track record of helping others achieve measurable growth.

Is CEPA coaching different from other coaching?

CEPA coaching applies that niche expertise to business development for your exit planning practice.

How do I choose the right business development coach?

Seek out a coach with appropriate credentials, industry knowledge, great reviews, and a style aligned with your goals and values.

What is included in typical business development coaching?

Coaching encompasses goal setting, business strategy, marketing and sales coaching, and ongoing support to assist you in plan implementation and measuring progress.

Can business development coaching boost my return on investment?

Yes, effective coaching can help you bring in more clients, close more transactions, and grow your practice, which translates into more revenue and a greater return on investment.

Ready to See How Coaching Could Accelerate Your Exit Planning Growth?

Discover where your practice stands and how business development coaching can help you scale smarter, faster, and with greater confidence.
Take the Financial Advisor Success Quiz to identify your growth opportunities and next best steps for building a thriving exit planning practice.

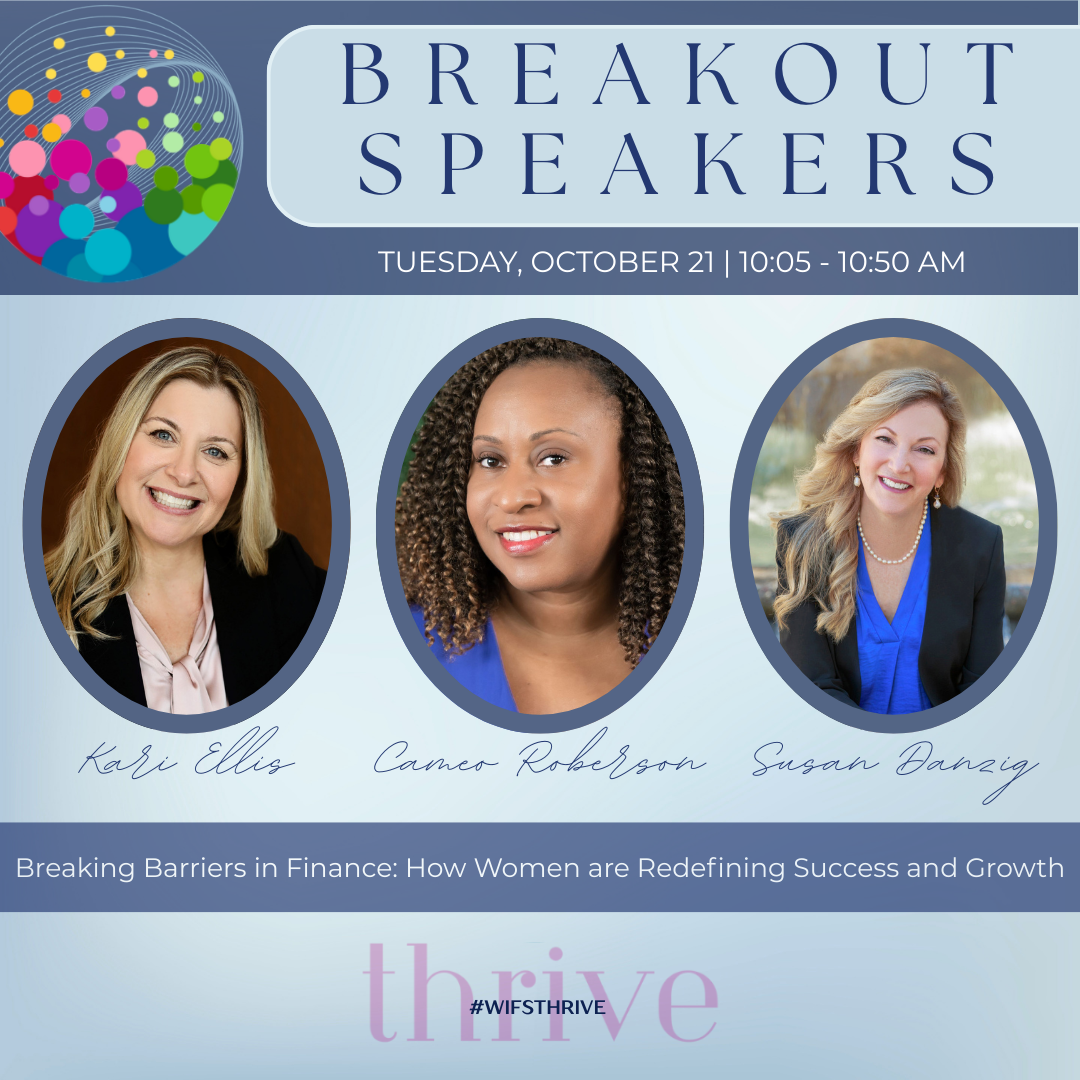
Breaking Barriers in Finance: Susan Danzig Reflects on WIFS 2025

Breaking Barriers in Finance: Susan Danzig Reflects on WIFS 2025

This past month, I had the privilege of joining my fellow Beyond the Broker co-authors at the Women in Insurance and Financial Services (WIFS) 2025 National Conference in Omaha, Nebraska. Together, we led a panel discussion titled “Breaking Barriers in Finance: How Women Are Redefining Success and Growth.”

A Space for Real Conversations

Our session was designed to spark honest dialogue around what it means to succeed as a woman in financial services today. From navigating independence to building client relationships rooted in authenticity, we shared personal experiences and actionable strategies that have shaped our own careers and those of the advisors we’ve coached and mentored.

The room was filled with incredible energy, genuine engagement, and powerful stories from advisors who are charting their own paths. Sometimes, the most meaningful conversations happen in intimate settings—and this session was a perfect reminder of that.

Beyond the Panel: Connection and Community

One of the greatest parts of any WIFS conference is the networking—on steroids! Throughout the event, I had the chance to reconnect with friends, collaborators, and new faces all united by a shared mission: to help women thrive personally and professionally in financial services.

The enthusiasm, openness, and collective wisdom in every conversation were deeply inspiring. I left Omaha feeling energized, motivated, and more committed than ever to supporting women as they build confidence, clarify their value, and grow thriving businesses.

Breaking Barriers in Finance: Susan Danzig Reflects on WIFS 2025

Moving Forward Together

The WIFS 2025 National Conference once again proved that when women come together to share insights and support one another, the entire industry moves forward. I’m grateful to have been part of that momentum and to continue advocating for women who are redefining what success looks like in this profession.

Thank you to everyone who attended, shared your stories, and connected during the conference. Let’s continue to break barriers—together.

???? Learn more about the WIFS National Conference
???? Explore Beyond the Broker: Navigating Financial Advisory Independence
???? Ready to grow your own practice? Let’s connect.

How to Turn Your CEPA Credential Into a Client Acquisition Machine

To turn your CEPA credential into a client acquisition machine means using your Certified Exit Planning Advisor status to win clients and grow your practice. A lot of owners need assistance with exit strategies, but they look for advisors who demonstrate competence, confidence, and a transparent process. Demonstrating your CEPA expertise in presentations, seminars, or manuals can differentiate you. Posting actual stories or case studies about how you’ve helped someone builds trust. Using your CEPA network for referrals works great, too. Keep it simple and speak to what clients value, such as frictionless exits or increased value. The meat will demonstrate step-by-step how to translate your CEPA credential into real client growth and provide tips for new advisors to differentiate.

Key Takeaways

  • Too many CEPAs don’t know how to turn their credentials into a client acquisition machine. Crossing this chasm takes more than the CEPA credential and well-crafted words. It requires a specific offer and messaging geared to business owners’ real-world worries.
  • Building a trust credential with clients starts by recognizing their misunderstandings and concerns around exit planning and solving these through holistic, customized answers that communicate the real value and enduring impact of expert advice.
  • If you want to take your CEPA credential beyond just another line on your resume and turn it into a client acquisition machine, then do this.
  • A strong marketing system should integrate digital, traditional, and referral channels to target and educate prospects through the client acquisition journey with ongoing measurement and optimization based on performance data.
  • By pivoting from a transaction to a relationship-based advisor mentality with the help of ongoing education, coaching, and systematization, you can create lifelong client loyalty that results in enduring growth for your practice.


By standardizing the way you onboard your clients, clearly communicating what they can expect, and collecting feedback along the way, you improve the client experience while increasing the efficiency and retention of your practice.

Corporate Training for Financial Advisory Firms

Why Your CEPA Is Not Working

Most CEPA holders assume that their credential will attract clients by itself, but this is almost never the case. It’s not primarily that your certification is good. Rather, it’s how the skills and knowledge get applied on a daily basis.

  • Identify common mistakes that CEPA holders make in client engagement.
    A common error is believing that technical expertise will attract customer confidence and recommendations. Most business owners are seeking obvious value, not buzz words or credential lists. When advisors discuss their process more than the owner’s needs, discussion falters. If you rely on generic email follow-ups or canned presentations, you miss the point. For instance, a CEPA who distributes the same pitch to all prospects will never discover the client’s actual pain points. This is why listening, asking the right questions, and demonstrating specific results are more important than service listing.

  • Recognize the gap between CEPA training and real-world application.
    CEPA training is about frameworks and best practices. Too often, advisors have difficulty translating these concepts into effective action. The real world is disorderly. Owners have split objectives, compressed schedules, and generally little tolerance for abstraction. A CEPA could know the Exit Planning Process end-to-end, but falter when a client asks, “How will this help me right now?” Bridging the gap means shifting from textbook steps to personalized advice. For example, rather than discuss “value acceleration,” demonstrate how a process change saved a previous client time or money with specific figures.

  • Assess the effectiveness of current exit planning strategies.
    Most CEPAs are either too inflexible or too high-level. They aren’t aligned to the client’s stage, industry, or specific risks. Too many CEPA holders apply a single template for every client, which produces bad results. Successful plans leverage actual data, respond to market changes, and take into account personal objectives as well as business objectives.

  • Evaluate the lack of a targeted marketing approach for your services.
    A generic marketing strategy will cost you time and money. Without focus, your message gets lost. Most CEPAs depend on word of mouth or hope their site will deliver leads, but that’s insufficient. Focused marketing is about understanding your perfect customer—whether it’s by industry, size, or requirement—and addressing them directly. For instance, instead of ‘I help owners exit,’ say ‘I help business owners in Moraga plan smooth exits and grow profit before sale.’

Develop a Clear Offer

 A clear offer is the foundation for transforming your CEPA credential into a compelling client magnet. Business owners want to hear what differentiates your services, what value you provide as a certified exit planning advisor, and what outcomes they can expect from your counsel throughout their exit. By describing your offer in terms of actual specifics, concrete examples, and a transparent process, you transform your credential from a label into a client magnet that addresses the hopes and trepidations of your market.

The Problem
Entrepreneurs fret over leaving value on the table, grappling with complicated financial and legal issues, or having no idea what comes next after they exit. A lot of people believe exit planning is just about selling a business or that it’s something to begin when retirement is close. Others fear losing control, tax surprises, or the effect on staff and family. These concerns hinder action or prevent owners from reaching out altogether. Generic service pitches don’t assist; they instead make it difficult for clients to understand why they should work with you and not anyone else.

The Solution
Tailored exit strategies are most effective when they begin with the individual client’s needs, business scale, and objectives. A good plan mitigates risk, delineates the steps, and addresses financial, operational, and personal issues. The CEPA credential means you utilize time-tested frameworks and receive dedicated training in the exit process. For instance, you demonstrated how you assisted a business owner in Moraga to plan a staged exit or collaborated with a family business to transition the firm to the next generation while minimizing tax costs and stress.

The Process
Begin with a comprehensive business and personal evaluation to identify hazards and expansion targets. Define clear objectives with the client, such as seamless transition, maximum sale value, or employee retention. Design a personalized strategy, then help the customer navigate value creation, due diligence, and negotiations with purchasers or successors. While the majority of exit plans occur in steps over 18 to 36 months, some require additional time or less.

The Outcome
Well-planned owners go out on their own terms, frequently with a higher sale price, less stress, and more legacy. One client doubled their valuation after two years of planning. Another kept key staff on board after exit. Stakeholders experience growth and stability, and the business legacy holds strong for years. Nothing like a clear plan for peace of mind and pride!

The Price
Clear pricing builds trust. Offer fixed-fee packages, hourly rates, or tiered services such as basic reviews, full exit plans, or ongoing coaching. For example, a base package could cover assessment and roadmap, while a premium one covers full support through closing. Make it clear that the right exit plan can add far more value than its cost through a higher sale price, tax savings, or a smoother handoff.

Build Your Marketing System

Converting your CEPA credential into a client acquisition machine is about constructing a well-defined marketing system that operates on multiple levels. You need a plan that fits the way you work and the people you want to reach. A plan puts down the rules of engagement, where and when you encounter potential clients, how you discuss your skills, and what you measure. Employing both online and offline channels enables you to reach people wherever they are. Clear content helps people know why exit planning matters. By measuring your results, you can be sure you are investing your time and money in what really matters.

Digital Channels

Social media, LinkedIn, in particular, is a bridge to business owners and others. You can distribute bite-sized tips, news, and success stories that demonstrate your elbow grease with exit plans. A consistent presence can make you more discoverable to those seeking assistance.

Email marketing is a great way to keep in contact with people who have expressed some interest. By giving business owners examples in the form of short case studies or practical guides, you can help them appreciate the benefits of planning ahead.

Make sure you’re discoverable online by SEO optimizing your website so when someone searches for exit planning, they find you, especially if you use plain language and share examples of your work. Webinars and online workshops allow you to demonstrate your expertise on the fly, answer questions live, and provide business owners with a sense of your working style.

Physical Channels

In-person meetings at local business events establish real trust. Handing out printed guides at these events provides entrepreneurs something tangible to bring back to the office.

Hold mini-seminars to explain the nitty-gritty of exit planning. These events are best when they focus on local issues or trends. Partner up with other local businesses, like law or accounting firms, to gain access to new audiences and accelerate word of mouth.

Referral Networks

A basic referral system, with tangible rewards for partners, provides other people to discuss your work.

Financial advisors and accountants already have your ideal clients. Meeting with them, sharing resources, and attending their events will help you construct a network that continues to grow. Trade shows are great places to meet new partners and learn from others in your industry.

The Advisor’s Mindset Shift

With a CEPA credential, how advisors think about their role has to shift. Instead of simply closing deals or providing one-off services, the mindset should shift to assisting owners plan their exit from their businesses over years—not days or weeks. This shift is about more than sales; it’s about establishing trust and positioning yourself as a true counterpart to clients. The table below shows what this shift looks like in practice:

Transactional Approach | Relationship-Based Approach

Single service or product sale | Ongoing value and advice
Focused on immediate needs | Looks at long-term client goals
Limited contact after the sale | Regular, proactive communication
Price-sensitive conversations | Value-driven, trust-based talks
One-time transaction | Multi-year partnership

That’s the growth mindset of the Advisor. Exit planning is not a static discipline. Regulatory rules, tax standards, and best practices can shift rapidly. To maintain your CEPA chops, reserve time each month to read new research or participate in remote workshops. There are global groups and online forums that update you on industry trends and case studies so it is easier to be one step ahead. For example, an advisor in Moraga or anywhere in the Bay Area can access the same white papers and webinars as peers across the country. This broad reach keeps each and every CEPA at the forefront, wherever they practice.

Confidence in your abilities as a CEPA is as much about how you demonstrate it as what you know. Owners want an explainer. They seek a sure hand to direct them through major decisions. Try walking them through previous case studies or an obvious step-by-step plan for how you operate. Illustrate, for instance, by taking the client through how you guided a previous owner to prepare for retirement with a well-defined exit road map or by leveraging actual results. This establishes credibility and demonstrates that your expertise is supported by tangible success, not just academic idealism.

Corporate Training for Financial Advisory Firms

Leverage CEPA Coaching

CEPA coaching is not just coaching. It’s a means to acquire skills, enhance credibility, and establish a business that converts your credential into a consistent flow of clients. Working with coaches, mentors, and peers closes gaps fast, keeps you current, and gives you tools to stand out in a crowded field.

Skill Gaps

Start with an honest look at your abilities. Identify what you don’t know and what bogs you down. Maybe you need more practice with client talks or want to know how to leverage valuation models better. That’s not technical stuff. Real growth is learning how to talk in ways that reassure clients they’re safe and heard.

Other CEPAs may not be certain how to identify emerging market trends or client needs. Coaching brings these weak spots to your attention. For instance, you could realize you’re uncertain of how to broach exit strategies with owners from certain cultures. A coach can role-play these talks, provide you feedback, and share what has worked for others.

Understand how to ‘read’ different types of businesses and their requirements. Have your mentor review actual cases with you, so you observe how specifics unfold in practice.

Accountability

Explain your goals in plain language. Monitor your advancement. Use periodic check-ins with a coach or peer group to hold you accountable for what’s going well.

Shatter your grand schemes into steps. For instance, try connecting with two new prospects a week or refreshing your pitch in a month. Discuss these aims with a mentor. If you slip, discuss what interfered and what you will attempt next.

Look back at your wins and misses every month. Tweak your plan. Good coaches can highlight blind spots or assist you in identifying patterns in what works optimally.

Systemization

Create easy, actionable steps for every segment of your journey. Detail how you onboard clients, what tools you use, and how you follow up.

Automate little jobs when you can—reminders, calls, report templates. This liberates you to dedicate more time chatting with clients and less with admin.

Utilize things like CRMs to make notes on leads and follow-ups. Email templates, onboarding checklists, and standard reports save time and keep you cutting-edge.

Streamline Client Onboarding

A streamlined onboarding process establishes the foundation for a robust client relationship. Having a CEPA credential demonstrates your expertise and trust. Your client onboarding process can create a powerful first impression and instill genuine confidence in your services.

Design a seamless onboarding experience for new clients.

Begin with a step-by-step outline that details each component of the process. Simplify and clarify, so clients understand the next step. For example, break down the journey into clear phases: introduction, document collection, needs review, and initial setup. Leverage digital forms or online portals where possible to save time and minimize errors. Demonstrate to clients that you respect their time and value their input by adhering to a predetermined schedule for each phase.

Utilize checklists to ensure all necessary information is collected.

A checklist keeps everyone on the same page and reduces lost details. Inventory all of the documents, data, and signatures you need from clients. Post the checklist early and keep updating it as you go. For instance, a basic digital checklist can prompt clients to upload ID, proof of ownership, and other necessary files in one location. This keeps you from wasting back and forth emails and accelerates the entire process.

Communicate clearly about the onboarding process and expectations.

Define rules for each process step. Your clients will appreciate knowing what to expect. Write in simple words and avoid legal or tech jargon that might be confusing. E-mail brief summaries after every meeting or call, so your clients always understand what was agreed and what comes next. For international clients, provide translations or define key terms if necessary, and always provide support contacts should they have questions.

Gather feedback from clients to continuously improve the onboarding experience.

Request feedback immediately following onboarding. Use mini-surveys or personal calls. Concentrate on what worked and what could be improved. Look for trends in feedback so you can address bottlenecks, such as sluggish paper reviews or confusing phases. Demonstrate to your clients that you value their opinion by sharing how you adjust things based on their feedback.

Conclusion

To leverage your CEPA magic for more work, keep things straight. Present your offer in manners that match what owners desire. Construct a strategy that generates leads, not just wish for fortune. Utilize every step, such as easy sign-up or intelligent conversations, to establish credibility. Keep your talk real and demonstrate what you can do to help, not just what letters you put behind your name. Stay sharp and connect with CEPA coaches or peer groups to keep your edge. Your proficiency expands with every triumph and every masterclass. For additional advice, join our blog, share your story, or request assistance. The more you give away, the more you expand in this arena.

Frequently Asked Questions

What is a CEPA credential?

A CEPA certifies advisors in exit planning for business owners. It signifies ‘expert’ and makes them trust you as a guide to show them how to transition their business.

Why is my CEPA credential not attracting new clients?

CEPA by itself is not a client magnet. You need a crisp offer, focused marketing, and efficient onboarding to transform your cepa credential into a client acquisition machine.

How can I create a compelling offer with my CEPA?

Identify clear business owner problems you solve. Just tell them what they’re worth. Concentrate on results like growing a business, mitigating risk, or an exit to get some attention.

What marketing system works best for CEPA advisors?

An educational-style digital marketing system with webinars and automated follow-up is great. This establishes trust, demonstrates your authority, and cultivates leads effectively.

How does mindset affect client acquisition for CEPA advisors?

A growth mindset enables you to pivot, learn, and approach potential clients with confidence. If you’re receptive to feedback and new strategies, you’re more likely to succeed.

What is the benefit of CEPA coaching?

CEPA coaching delivers personalized guidance, proven strategies, and accountability. It helps you get the best practices implemented quicker and avoid the pitfalls of common mistakes in client acquisition.

How can I streamline my client onboarding?

Use transparent processes, online tools, and regular communication. This establishes trust immediately and guarantees a seamless experience for each new client.

Turn Your CEPA Credential Into a Client Acquisition Machine

You’ve earned your CEPA—now it’s time to make it work for you. If you’re ready to attract more ideal clients, strengthen your marketing message, and turn your credential into a powerful business growth tool, don’t go it alone.
Schedule your CEPA Growth Consultation and discover how the FAST Program can help you position your expertise, clarify your offer, and systematize your client acquisition process for consistent results.

Should You Outsource Business Development Coaching For Your Financial Advisory Team?

Outsourcing business development coaching for your financial advisory team can inject new expertise and offer fresh perspectives from external professionals. A lot of firms experience increases in team motivation, improved sales conversations, and actionable strategies aligned with market demand. Outsourced coaches tend to be in touch with the latest tools and techniques, so teams acquire good habits that linger. For teams that want to grow quickly, external assistance can plug expertise gaps without permanent additions. Internal training can be less expensive and can align with a firm’s own culture more effectively. To decide if outsourcing is the right move, it’s useful to examine your team’s objectives, available funding, and where skills are lacking.

Key Takeaways

  • Business development coaching outsourcing offers specialized expertise, industry insights, and proven frameworks that can enhance your advisory team’s performance.
  • Outside coaches provide an objective perspective on your firm’s strengths and weaknesses, assisting in uncovering blind spots and refocusing strategies to address changing market needs.
  • Scalable outsourced coaching is equipped to handle growth, keep training consistent, and meet the evolving needs of your organization’s diverse teams.
  • This requires a careful cost-benefit analysis because outsourcing can reduce hidden costs, enhance advisor productivity, and provide a significantly better ROI than in-house programs.
  • Here’s what you want to look for when choosing an outsourcing partner: check their credentials, make sure that they align with your firm’s culture and goals, and ask for proof of measurable results.
  • To do outsourced coaching well, you need to communicate clearly, onboard the outsourcers with your culture, define success metrics, and ensure ongoing compliance with industry regulations.
Corporate Training for Financial Advisory Firms

Why Outsource Business Development Coaching?

Outsourcing business development coaching has become a viable option for financial advisory firms aiming to enhance their competitive edge in a rapidly evolving market. By partnering with Susan Danzig, firms can introduce a blend of industry expertise and objectivity that is challenging to develop internally. Working with an experienced business development coach facilitates skill growth while allowing firms to easily scale resources based on business cycles. This strategy is especially effective for international teams, who thrive on flexibility and efficiency.

1. Specialized Expertise

Experienced business development coaches from external organizations frequently have a strong understanding of the financial services industry. These experts from advisory firms have experience working with a number of advisory firms, so they have firsthand knowledge. Their job is to fine-tune and refresh your firm’s business development strategies, providing you with fresh strategies that are customized for the financial advisory reality.

One such benefit is access to coaching for specific problems to solve, such as managing business development alongside client work or adopting new technologies. This needed support is custom-fit for seller-doers, whose time is spent doing client work, not business development. By integrating specialized coaching techniques into your training schedules, you can enhance advisor performance and inspire continuous skill development.

2. Objective Perspective

Outsourced coaches provide honest, unbiased feedback. They’re not bound by internal politics or legacy processes, so their evaluations strike at what works and what doesn’t. This outside perspective helps to identify blind spots in your firm’s current approach and can expose gaps that internal teams may miss.

A little constructive criticism can ignite growth, question assumptions, and generate genuine improvement. Objective reviews help you adjust your goals to what the market and clients now expect.

3. Scalable Growth

By partnering with outsourcing providers, you can effectively scale your business operations during peak seasons and reduce your team size when it’s slower, providing crucial flexibility for growing organizations. This approach allows you to explore outsourcing solutions that enhance efficiency and adaptability.

Moreover, deploying consistent training firm-wide while customizing the program for various business models ensures that every financial advisor, whether junior or senior, receives reliable, top-notch assistance.

4. Proven Systems

Outsourced coaches bring in systems and strategies proven by other companies. These frameworks simplify your coaching, minimize guesswork, and emphasize explicit, quantifiable results.

By using proven strategies, your team works intelligently and achieves more.

5. Renewed Focus

When coaching is taken care of by an outside partner, your team can focus more time on client acquisition, engagement, and other primary work. This change minimizes interference from internal training and fosters a more efficient workspace.

Professional development is prioritized and, therefore, keeps your consultants cutting-edge and driven to succeed.

The In-House Coaching Dilemma

About The In-House Coaching Conundrum. In-house coaching allows a company greater control over how it trains its financial advisory team. In-house gurus can determine the schedule, duration, and location of each session. This aids in squeezing coaching into hectic workdays and facilitates coordinating team schedules across the globe. In-house coaches understand the company culture, pressure points, and daily grind. They can tailor advice to what the team is confronting at the moment. This is good for trust-building and keeping lessons close to the day-to-day work. For some firms, this control and deep knowledge help them save money, as they don’t have to hire an outsourcing provider each year.

Still, in-house coaching has obvious boundaries. Teams can become trapped with a single mindset. When all counsel is in-house, concepts begin to echo, and fresh means to address issues do not emerge. Bias is a real danger. In-house coaches may not notice skill gaps or may avoid difficult conversations that can propel someone forward. For instance, a coach who has toiled for years in a firm may not push back on habits or may skirt topics that challenge the status quo. This can decelerate growth and prevent teams from peaking, making it imperative to explore outsourcing solutions when necessary.

Handling in-house coaching requires tons of resources. It takes time and costs money to train a good coach. This is the case for any firm, but it becomes more difficult as the team expands. If a firm is adding new staff in new locations, it requires more coaches or more hours from the same individuals. This can spread teams too thin, rendering the coaching less valuable. Outsourcing business advisory services can bring in business growth expertise, but without familiarity with a firm’s unique ways or values. It can be expensive to hire outside coaches, but they frequently deliver new thinking and new capabilities.

The Financial Equation

Outsourcing business development coaching for financial advisory teams can transform the economics of firms. By exploring outsourcing solutions, businesses can compare internal efforts with outsourced business advisory services, examining all costs, return on investment, and how well each model supports advisors in building client relationships in a saturated market.

Cost Analysis

Cost Category

In-House Coaching (USD)

Outsourced Coaching (USD)

Trainer Salaries/Fees

50,000/year

30,000/year

Program Development

15,000

Included

Materials and Tools

5,000

2,000

Staff Time
(Lost Productivity)

20,000

5,000

Ongoing Updates

8,000

Included

Total Annual Cost

98,000

37,000

Deep internal training can hide costs not initially apparent, including staff time spent on planning and lost productivity when advisors are pulled from their primary responsibilities. For instance, if in-house sessions pull advisors from client meetings, the opportunity cost can grow quickly. Outsourced business advisory services generally combine materials, program updates, and expert advice, making their costs more straightforward to anticipate and control. While not all firms will see savings if their requirements are very specialized, utilizing an outsourcing provider can help retain full content control while still benefiting from expert guidance.

Outsourcing options can decrease attrition and develop advisor competencies more rapidly, ultimately reducing hiring and onboarding costs. For some global companies, outsourced planning providers offer custom packages that accommodate fluctuating budgets, such as monthly, quarterly, or per session. A close cost-benefit analysis can help firms see where the true value lies, weighing costs against the suitability of the coaching model for their advisor team.

ROI Projection

  1. Gather initial information on advisor productivity, client capture, and retention.
  2. Project enhancements involve examining results from comparable companies that employed outside coaching, particularly in their expansion of client interest and their portfolios.
  3. Revenue impact equals new clients multiplied by the average fee per client minus external coaching cost.
  4. Monitor advisor attrition. Measure advisor turnover and compare it to industry benchmarks.

Based on historical data, companies can predict a 10 to 20 percent increase in client retention when coaching is aimed at relational skills, which are crucial in financial advisory services. Business-challenged advisors might grow more with an outsourced business advisory services coach than they do working with a third-party lead generation consulting service, which some consider a waste of time. Firms need to track advancement over time and look for increased income and advisor contentment.

Choosing Your Partner

Choosing your partner is crucial in the realm of outsourced business advisory services, especially for financial advisors. It’s not merely about filling a gap; it’s about selecting an outsourcing provider who aligns with your long-term strategic vision and complements your trusted advisors. The most successful partnerships are those where each party understands its strengths, acknowledges its vulnerabilities, and maintains flexibility in communication and collaboration. It’s important to look beyond short-term victories and ensure the coach’s style aligns with your team’s mission and culture, while also exploring outsourcing solutions that offer customizable plans.

Assess Credentials

A nice first step is to see if the outsourced business advisory services provider’s team has the appropriate background. Seek out professional training, industry certifications, or accolades that demonstrate they understand the craft. A background in financial advising is crucial. The issues your squad grapples with, such as policy changes, customer confidence, and hard deadlines, need a mentor who speaks your language, not some generic corporate babble.

It’s always good to see some case studies or client remarks, particularly from companies of your size or market. That provides a feeling for whether the coach can pull off actual results. Some outsourcing providers exhibit client wins, but press for specifics. Were objectives achieved? Did teams experience real growth in meetings or conversions?

The best coaches are very well-connected. They know the ins and outs of the financial services world and can describe how they adjust to new market rules or technological shifts. If your team is global, ensure the provider has worked cross-culturally and can bridge gaps in work style or talk.

Verify Alignment

Make sure the coach’s values align with your own! Discuss your company’s objectives and observe whether the vendor hears you and comprehends. If your team appreciates open conversation and experience-based learning, the coach ought to do so.

Inquire how they adapt to align with your work style and team habits. Does their plan conflict with your consultants’ day-to-day methods? The right partner fits in without resistance.

Try their ideas against your business model. A good partner will never impose a one-size-fits-all plan. They will customize their curriculum to help you achieve your own goals, not just industry averages.

Request Proof

Request evidence of achievement. This might be figures such as an increase in client retention or new business signed post coaching. Explore sample plans to view your team’s activities week by week.

Seek references from other companies. Extend your network and listen for candid feedback. Did the provider keep his promise? Were the results obvious and enduring?

See if their process allows you to monitor progress. Can you see results in raw numbers, not just anecdotes? This makes it easy to judge if the partnership is working or if you need to change direction.

Corporate Training for Financial Advisory Firms

The Integration Blueprint

An integration blueprint for outsourcing business development coaching is a strategic approach to blending outside expertise into a financial advisory team’s daily operations. At Susan Danzig, we design customized integration plans that align seamlessly with your workflows, ensuring that coaching initiatives enhance, not disrupt, your existing business processes.

Our blueprints define how to embed professional coaching into your systems, establish clear communication channels, and set performance metrics that demonstrate measurable improvement. The goal is to help firms combine external insights with internal strengths, allowing business growth initiatives to run smoothly, leaner, and more effectively.

A practical integration blueprint includes these steps:

  1. Survey current biz dev flows and plan where coaching will integrate.
  2. Define all the pieces: internal groups, outside coaches, data platforms, and the links required among them.
  3. Establish open data formats and protocols so information can flow easily between your company and the coaching partner.
  4. Map out an onboarding and training timeline, along with a continuing review timeline that includes checkpoints for gauging progress.
  5. Construct feedback loops to continuously refine the integration according to advisor performance and business requirements.

Cultural Onboarding

Ensuring the outsourced coaching partner is aligned with your firm’s culture sets the stage for trust and productivity. Your onboarding should provide coaches with a strong impression of your philosophy, ethics, and team culture. Schedule in-person or virtual meetings where coaches and advisors can get to know each other and build rapport, creating a comfortable environment for both sides to operate as a single unit. By providing materials like company handbooks and client playbooks, you can customize the coaching experience to your environment. A joint onboarding session where internal teams and outsourcing providers can ask questions and establish shared goals makes everyone feel committed.

Communication Cadence

Regular communication is essential for effective vendor management and keeps integration on target. Weekly or biweekly check-ins allow both your firm and the outsourced business advisory services partner to exchange updates, flag problems, and establish near-term priorities. Determine in advance how frequently you’ll meet, what instruments you’ll use (video calls, project boards, IM), and who should attend each meeting. Advisors should feel comfortable providing immediate feedback to coaches, fostering trust and speeding up issue resolution. Utilizing a common dashboard or collaboration platform keeps everyone updated on objectives, timelines, and outcomes.

Success Metrics

The blueprint must define what success means, focusing on quantifiable objectives like percentage client growth or enhanced advisor output, essential metrics for business advisory services. By selecting key performance indicators (KPIs) and monitoring them monthly, you can explore outsourcing solutions if the numbers don’t reflect your desired gains. Celebrate victories and share wins with the team to maintain enthusiasm and support momentum.

Navigating Compliance Considerations

There is a new set of compliance considerations that come with outsourced business advisory services for financial advisory teams. While financial firms do need to scale, they must navigate compliance considerations diligently. Regulators want firms to maintain a grip on every third-party partnership, making it essential to understand what to look for when selecting an outsourcing provider and how to uphold these standards.

  • Verify that the coaching service meets all regulatory and legal compliance requirements for financial advisory work.
  • Ensure your vendor has a robust data security policy and protects sensitive client data.
  • Make sure the coach or firm has compliance training and can educate your team on recent regulations.
  • Under strict rules, establish clear policies on sharing information and managing confidential client information.
  • Check your outsourcing contract for detailed compliance responsibilities, audit schedules, and reporting requirements.
  • Establish periodic audits and reviews of compliance to identify gaps and repair them quickly.
  • Request evidence of continuous compliance training for all coaches’ personnel and your members.
  • Ensure that your partner has a track record of strong compliance without previous breaches or penalties.

Regulators now expect firms to show they can manage their vendors, especially when those vendors deal with sensitive data or compliance tasks. This means you need to check not only how the coach teaches but also how they store and utilize your client information. Strong vendor management practices, such as routine checks and risk reviews, help keep your firm compliant with the law while protecting your business. Some firms even outsource compliance checks to experts, allowing them to focus their staff on growth and client service.

Strong compliance builds lasting trust with clients and demonstrates that your firm prioritizes integrity, transparency, and accountability, values that Susan Danzig upholds in every engagement.

Final Remarks

Outsourcing business development coaching with Susan Danzig gives financial advisory teams a strategic advantage. You gain access to specialized expertise, fresh perspectives, and actionable training that produces results fast. Our team helps eliminate inefficiencies, refine advisor performance, and ensure compliance, all while maintaining focus on measurable growth.

In-house coaching can work for some, but partnering with Susan Danzig often accelerates success, deepens accountability, and helps firms adapt confidently to industry change. To move your team forward, consider which approach aligns best with your goals, and focus on results that truly drive performance.

Frequently Asked Questions

1. What Are The Main Benefits Of Outsourcing Business Development Coaching?

Outsourcing provides access to expert coaches and outsourced business advisory services, offering new perspectives and battle-tested strategies that can rapidly up-skill your team, save time, and be more cost-effective than hiring and training internally.

2. How Does Outsourced Coaching Compare To In-House Coaching?

Outsourced coaching offers expertise and flexibility, while in-house coaching may provide a more tailored approach. Both options suit different business models and objectives, making them viable outsourcing solutions.

3. Is Outsourcing Business Development Coaching Cost-Effective?

Yep, it’s usually cheaper to utilize outsourced business advisory services. This approach minimizes the costs of recruitment, training, and continued employee administration, allowing you to pay solely for what you require and optimize ROI.

4. What Should I Look For In A Business Development Coaching Partner?

Select an outsourcing provider that has a proven track record, industry experience, and results. Ensure they align with your corporate culture and can customize their business advisory services to your team’s specific requirements.

5. How Do We Ensure Compliance When Outsourcing Coaching?

Choose outsourced business advisory services partners who understand your industry’s compliance. Inquire about their compliance experience and seek references to ensure effective vendor management.

Let’s Design A Custom Program For Your Firm

At Susan Danzig, we understand that no two financial advisory teams are alike, and that’s exactly why every coaching program we build is customized to your firm’s goals, growth stage, and market position. Whether you’re exploring outsourced business development coaching for the first time or looking to enhance your existing training, we’ll help you create a structured, measurable program that drives performance and accountability across your team. From leadership alignment and communication strategies to client acquisition frameworks and compliance integration, we design every element to support sustainable, long-term success.

Let’s design a custom program for your firm, one that strengthens your advisors, scales your results, and helps you achieve the business growth you’ve been working toward. Schedule a consultation today to begin shaping your firm’s next level of success.

Case Study: How One Advisory Firm Increased Production By 30% With Structured Coaching

At Susan Danzig, we’ve seen firsthand how a well-designed coaching framework can transform an advisory firm’s performance. This case study explores how one firm increased production by 30% through structured coaching, using the same principles and strategies we teach to our clients.

The firm employed periodic goal setting, skill checks, and candid conversations with employees to identify weak points and amplify what worked. Managers partnered with staff weekly, providing transparent feedback and actionable paths for incremental growth. Rather than generalized training, the firm selected bite-sized daily activities that aligned with actual client requirements. Results followed within months as teams collaborated more effectively and reached new sales records. To share what worked, the remainder of this post will unpack the steps and tools the firm deployed and why these shifts resulted in such powerful growth.

Key Takeaways

  • Identifying production plateaus and their root causes is essential for firms seeking to increase efficiency. A structured assessment can highlight workflow inefficiencies and leadership gaps that hinder growth.
  • Working with Susan Danzig, they built a coaching framework specifically tailored to their organizational goals and best practices. This allowed the firm to approach specific performance challenges with precision and clarity.
  • Coaching sessions at regular, rhythmic intervals that promote collaboration and accountability drive learning and keep both advisors and leaders engaged in the process.
  • Leadership commitment and involvement are essential to establishing a culture of accountability and validating coaching across the firm.
  • By quantifying both the concrete aspects, including increases in production and advisor stickiness, and the less measurable aspects, such as morale and client loyalty, you can provide a more holistic perspective on coaching’s ROI.
  • Firms should expect implementation hurdles and proactively combat resistance with continued support, success stories, and adaptive approaches in order to fashion lasting productivity and growth improvements.
Corporate Training for Financial Advisory Firms

The Firm’s Production Plateau

A firm’s production plateau can stop its growth and diminish its competitive edge in a saturated market. When production output ceases to grow even as demand remains steady, firms typically encounter both increasing costs and diminishing profit margins. In other words, the advisory firm encountered a plateau. Its executives observed expenses rise and margins decline, but production remained stuck. Here is a breakdown of what caused the stagnation and its impact.

Factor

Impact

Outdated systems

Caused slow workflows and missed chances for higher output

Inefficient automated systems

Made errors more likely, led to more work, and wasted time

No standard procedures

Raised costs by 20%, cut output, and caused more mistakes

Supply chain problems

Pushed operating costs up by 20%, delayed work, and hurt reliability

Rising raw material costs

Shrunk profit margins by 15%, making it hard to keep up with competitors

Higher labor costs

Squeezed margins further, limited how much the firm could reinvest

The firm’s production plateau was still underpinned by manual checks and legacy software that simply could not keep up with the demands of its sales process. Every process step had its own thing, no communal workflow or checklist. Consequently, teams worked harder patching errors, validating work, and waiting on approvals. These measures bogged down production and obscured opportunities for identifying inefficiencies. Automated tools like jidoka were supposed to smooth things out, but without constant updating or training, these systems became a source of errors and confusion, stalling their consulting success.

A structured approach was necessary, as the firm experienced too many lost hours and too many missed opportunities to grow their client engagement strategies. Without fixed methods, it was almost impossible to measure progress or implement real change. Teams got used to plugging holes as they came up, rather than searching for root causes and permanently shutting them. This reactive mindset made it difficult to increase production or reduce expenses. To escape this rut, the firm required new processes, defined action steps for every activity, and continuous training through a robust mentorship program.

Leadership brought both the plateau and the push for change. When leaders stuck to quick fixes, problems piled up. After the leadership team began owning and seeking permanent solutions, that’s when things started changing. They realized that a little goal setting, providing your team with the appropriate tools, and making training a regular occurrence could help increase production and reduce expenses.

How Structured Coaching Worked

For the advisory firm, structured sales coaching with Susan Danzig meant a methodical process with precise milestones. It allowed space for evolution as the team learned through effective mentorship. Goals were set and checked, ensuring everyone was aware of their progress, while accountability served as the secret sauce. Group support maintained momentum and high motivation levels.

  • Conduct an initial assessment of firm capabilities and practices
  • Build a coaching framework tailored to the firm’s goals
  • Schedule regular coaching sessions for steady progress
  • Secure leadership support and model desired behaviors
  • Develop skill modules focused on real needs
  • Gather feedback and refine the coaching process continuously

1. Initial Assessment

The company began by examining advisors’ sales process and existing knowledge through business research insights. They engaged in client interactions and reviewed feedback to identify vulnerabilities, which highlighted the need for effective sales coaching. The team established concrete goals, such as the number of new client opportunities each advisor acquired and their deal-closing speed, providing a baseline for progress checks.

2. Tailored Framework

A tailored sales coaching plan was crafted around the organization’s objective, with steps aligned to daily habits. By integrating established best practices from the coaching industry, it was customized to fit the firm’s size and ideal clients. For instance, one advisor rapidly refined their website and LinkedIn profile, leading to significant improvements. This roadmap made structured coaching a success, helping another advisor secure his first paying client within just two weeks.

3. Rhythmic Sessions

Coaching was weekly, and this regular cadence ensured that lessons adhered and actions came to fruition. With each meeting building on the last, skills grew, particularly in areas like sales coaching and client engagement strategies. These sessions allowed individuals to discuss practical issues, such as pricing services or improving proposals, ultimately leading to significant improvements in business performance. Attendance was monitored, but the true evidence was in outcomes, as one consultant secured his sixth client through effective mentoring within mere group meetings.

4. Leadership Alignment

Leaders supported the coaching process from day one, participating in sessions to share victories and insights, which made sales coaching feel significant rather than a side hustle. This engagement fostered a culture of accountability and encouraged team members to keep each other honest, ultimately enhancing client engagement strategies.

5. Skill Modules

Skill modules focused on critical areas such as making proposals and setting fees, essential for effective sales coaching. Advisors practiced with real assignments, like writing a pitch or refining a marketing plan, which significantly improved their consulting success. Feedback was candid, leading one advisor to quintuple his fees after a pricing module, demonstrating the impact of structured mentorship in the consulting industry.

Measuring the 30% Increase

As Susan Danzig teaches in our coaching programs, measuring production growth begins with clear, consistent tracking of key metrics. For advisory firms, you need to know what to measure before and after coaching. Common metrics tracked include:

  • Total number of client meetings per month
  • Number of new clients onboarded
  • Revenue per advisor (in EUR or USD)
  • Client retention rates (percentage)
  • Follow-up actions completed within set timeframes
  • Volume of cross-sell or upsell activities
  • Average client satisfaction score (measured on a standardized scale)

Measuring these metrics provides companies with a baseline to evaluate shifts over time. To measure a 30% increase, the simple formula is: New Value minus Old Value divided by Old Value equals 0.30. This implies that if an advisor were at 100 client meetings per month and, after coaching, reached 130, that is a 30% increase. This estimate is easy to calculate with nice round numbers. When big data or moving targets are involved, it can get tricky. Data can flow from various sources or have a non-standard definition, which complicates obtaining accurate numbers. Some firms address this by constructing dashboards that aggregate data from all avenues and display trends in a single location. For instance, a dashboard might display total revenue per advisor rising from €10,000 to €13,000, showing without question that a 30% increase occurred.

That’s where the coach analyzes the data to determine if the coaching was effective. Companies have bar charts and line graphs to measure production increases. These graphics enable leaders and stakeholders to visualize the results quickly, simplifying the coaching’s storytelling. For instance, a paper might note that after six months of coaching, retention increased from 70% to 91% and revenue per advisor increased by 30%. These images establish confidence and demonstrate impact, particularly to teams and clients who crave evidence of expansion.

Establishing benchmarks is equally crucial for the future. Once a 30% increase is measured, firms have new numbers to base future planning on. They monitor trends and have reasonable targets, like another 10% growth next year. That cycle of measuring, reporting, and goal-setting keeps the firm focused and moving forward.

The Invisible ROI Of Coaching

Coaching often delivers more than just higher numbers. Its primary benefits are invisible on spreadsheets, yet their impact is profound. Coaching transforms the way people work and think, enabling teams to build trust, develop skills, and retain clients for the long term. Research finds that 77% of companies report a significant transformation in a key business area as a result of coaching. This transformation is more than goal attainment; it is about incremental improvements in how people collaborate and serve clients, enhancing the overall sales process.

Intangible Benefit

Effect On Business

Employee morale

More drive, less turnover

Job satisfaction

People stay, want to improve

Client retention

Clients come back, trust builds

Loyalty

Staff and clients commit longer

Coaching can get people to connect with clients differently in the long run. When employees learn to listen, establish actionable steps, and problem-solve, customers notice. Improved skills make discussions flow more easily and solutions arrive sooner, enhancing client engagement strategies. It makes clients happier and stickier. Over time, this creates trust and loyalty. Employees who experience being listened to and supported through mentoring communicate that support to customers. Companies that maintain coaching achieve greater client loyalty, which is essential for sustainable expansion.

As skills mature, employees make wiser decisions every day. Even a 10% enhancement in decision-making can lead to big wins over a two or three-year period. About 60% of executives connect coaching to actual economic value. It not only influences profits but also impacts people. When employees feel good and are equipped with the appropriate tools, their work improves, leading to better service, fewer errors, and more business from happy clients.

Fueling long-term growth by investing in people is crucial. The top performance return on investment occurs when firms view coaching as a habit, not a salve. The real test is what happens in between sessions, self-checks, experimentation, and new habit-building. Without this, coaching fades and gains vanish. Statistics illustrate the effect of coaching in 90 to 120 days, such a brilliant and fast way to grow, especially for organizations focused on consulting success.

Corporate Training for Financial Advisory Firms

Implementation Breakthroughs

Adding regimented sales coaching to an advisory firm’s work stream can significantly increase productivity. The road is strewn with potholes, and other firms encounter similar challenges when attempting to embed coaching into their everyday work processes. These obstacles are not confined to a single location; they arise in teams across various organizations.

  • Lack of buy-in from staff or managers
  • Unclear goals and weak planning
  • Fear of change or loss of control
  • Not enough support or resources
  • Poor communication between teams
  • Slow feedback and missed progress checks
  • Skills gaps and uneven training

Getting past resistance is essential, particularly when employees or leaders resist due to uncertainty about what to expect or a lack of perceived value. To address this, it is vital to be transparent about objectives and strategies. Communicate the ‘why’ and ‘how’ of coaching, and utilize business research insights to demonstrate how an implementation plan and defined objectives can accelerate outcomes. For instance, well-planned firms reach their improvement goals sixty percent more quickly. Engage people in determining these objectives so they can drive the process, and meet regularly to review progress, discuss pain points, and make necessary adjustments. This approach ensures that everyone feels heard and empowered to help mold the change.

Providing continued support and the appropriate tools is crucial for success. Teams need clear directions, checklists, and steps to implement effective client engagement strategies. Cross-training addresses skill gaps and fosters inclusion. Leadership training equips managers with tools to set a positive example and become agents of change. Maintaining open channels between staff, coaches, and leaders allows for convenient discussions about what works or does not. When things derail, viewing it as an opportunity to learn rather than a cause for blame fosters resilience and momentum.

Sharing actual successes is very helpful. For instance, a team that transitioned from ad-hoc conversations to scheduled coaching sessions experienced a 30% increase in output in under a year. Disseminating these types of stories provides hopeful and concrete evidence that the work is worthwhile. It demonstrates that the start is difficult, but the benefits can be huge for all participants.

Your Firm’s Actionable Blueprint

A smart plan is crucial for any firm seeking actionable gains in its sales coaching efforts. Seventy-one percent of leaders report their organization is flourishing when they employ a blueprint like this. The case study demonstrated, in detail, how a simple stepwise actionable plan produced a thirty percent output increase through disciplined mentoring. This blueprint for your firm’s actionable strategy helps establish the right habits, tools, and checks so that firms can achieve consulting success, even in brutal or fast-moving markets. Here’s a practical, numbered outline that any firm can follow to achieve similar success.

  1. Establish a coaching skeleton. Begin by sketching the muscle groups your squad actually requires assistance with, such as messaging, pricing, or fresh business models. Give every coach a clear focus and pair them with employees based on skill gaps and growth goals. Schedule regular sessions, weekly for the first three months, then every other week. This keeps the process moving and allows you to identify successes or problems quickly.
  2. Define milestones and timelines. Mark out micro victories that demonstrate momentum, such as completing a client pitch, sealing a deal, or conducting a pilot project. Try a 6-12 month horizon. Every two months or so, use a checkpoint to take stock and adjust the plan. This provides teams with specific objectives to build toward and enables leaders to detect patterns earlier.
  3. Use simple, universal tools. Select tools situationally: shared digital dashboards, project trackers, and feedback forms. Rely on video platforms for your coaching calls and cloud-based docs for sharing notes and goals. To accelerate AI adoption, integrate foundational AI capabilities for data verification and reporting. Twenty-four percent of firms have AI implemented firm-wide, and several executives anticipate further expansion.
  4. Prioritize upskilling and digital labor. Upskill workers so they can assume more complex work. Forty-seven percent of leaders say this is a primary objective. Give them actionable projects and authentic feedback, developing their capabilities from the start. Augment your workforce with digital labor. Forty-five percent of executives plan to augment their team with digital labor within the next 12 to 18 months.
  5. Adapt, review often. Review results every couple of months. Seek input, review impact metrics, and adjust the strategy as necessary. Executives are already hiring AI trainers to train teams on new tools and anticipate agent management becoming part of their role, freeing up precious hours each day.

Final Remarks

Structured coaching with Susan Danzig didn’t just help this firm break out of a rut. It provided the team with tangible methods to improve, work smarter, and achieve loftier targets. A 30% lift in production is eye-catching, but the real story lies with the individuals. Each individual acquired new skills, established confidence, and tracked his or her own growth daily. Coaching made the change stick because it fit the team, not just the metrics.

At Susan Danzig, we believe that structured coaching provides a specific roadmap and new momentum that any advisory firm can apply. Firms everywhere hit slowdowns or old habits that just won’t die, but with the right structure, consistency, and accountability, transformation is always within reach.

Frequently Asked Questions

1. What Is Structured Coaching In An Advisory Firm?

Structured coaching is an intentional, organized method to cultivate skills and habits, enhancing employee engagement. It leverages regular sessions, clear objectives, and quantifiable results to guide team members in the sales process.

2. How Did Coaching Lead To A 30% Production Increase?

The firm leveraged structured sales coaching to help advisors set goals, keep track of progress, and provide feedback. This approach inspired workers and improved employee engagement, generating a 30% boost.

3. What Metrics Were Used To Measure The Production Increase?

The firm monitored metrics like client acquisition, project completion, and revenues, showcasing how effective sales coaching can lead to significant improvements, as one advisory firm increased production by 30%.

4. Is Coaching Cost-Effective For Advisory Firms?

Yes. Though business coaching is an investment, the returns of higher productivity and better staff retention often justify the expenditure, leading to consulting success for numerous organizations.

5. What Are Common Challenges When Implementing Coaching?

Usual suspects include resistance to change, lack of time, and fuzzy goals. Overcoming these challenges requires effective sales coaching, leadership buy-in, clear communication, and continued training.

Schedule Your Own Assessment

Are you ready to see what structured coaching can do for your firm? At Susan Danzig, we help financial advisory teams uncover hidden growth opportunities, boost production, and build a stronger foundation for long-term success. Just like the firm in this case study, you can identify performance plateaus, strengthen your leadership alignment, and achieve measurable gains with a personalized coaching framework. Our process starts with a simple, powerful step, an individualized assessment that reveals where your firm stands today and what changes will deliver the greatest impact.

Take the first step toward transforming your firm’s performance. Schedule your own assessment with Susan Danzig today.

What Makes A Great Business Development Coach For Financial Advisor Teams?

At Susan Danzig, we help financial advisors learn how to attract more ideal clients without burning out by focusing on people skills, time use, and sustainable systems. Advisors who listen well, establish healthy boundaries, and apply intelligent technology tend to gain client confidence and maintain their practice with ease. Providing regular feedback, sharing real-life stories, and encouraging advisors to celebrate their victories all contribute to enhanced team development and morale. Training is most effective when it blends real-world experience with collaborative learning, so advisors develop habits that last. By leveraging these fundamentals, Susan Danzig helps firms and advisors attract ideal clients while keeping burnout low.

Key Takeaways

  • By knowing exactly what ideal clients look like and require, financial advisors can customize their offerings, focus their promotion, and provide more targeted engagement even in different markets.
  • Instead, by embracing a sustainable training framework that combines both technical and interpersonal skills and structured feedback mechanisms, you foster long-term advisor growth and alignment with organizational goals.
  • Instilling a growth mindset and self-reflection in advisors promotes resilience, prevents burnout, and nurtures lifelong learning.
  • By bringing clarity around niche markets and a clear value proposition, you help advisors attract and retain ideal clients, those best suited to their strengths, for more fulfilling and effective relationships.
  • By developing sustainable marketing and intentional networking strategies backed by digital tools, regular communication, and relationship-building experts, advisors extend their reach without sacrificing themselves.
  • Leadership needs to take the lead in advisor well-being, setting the tone with example, modeling sustainable work-life balance, and providing opportunities for personal and professional development, and routinely measuring the KPIs that ensure advisors stay happy and successful.
Corporate Training for Financial Advisory Firms

Redefine The “Ideal Client”

Training financial advisors to bring in more ideal clients begins with a solid understanding of who those clients really are. At Susan Danzig, we emphasize the importance of aligning the right financial advice to the right person so advisors spend their time and talents where they work best. Certain advisors flourish assisting doctors with student loans, while others excel in helping pre-retirees prepare for early retirement and travel. Once advisors know these details, they can tailor their services, speak directly to those clients’ needs, and avoid mismatched relationships.

Knowing your ideal client is about more than just numbers or job titles. It’s about understanding what drives these customers, what fears they have, and what economic challenges they face. A doctor with a big student loan balance may need tips for how to pay off debt while building a practice. A friend flirting with retirement might require advice on income planning, health insurance decisions, or smart Roth conversions. Advisors who dig deep into a particular group can bring more to the table. They know more hacks, resources, and alternatives that suit those individuals best. That results in more trust and greater outcomes for both parties, enhancing the overall client engagement experience.

With a well-defined profile of the client they desire, advisors can adjust their marketing and outreach accordingly. They don’t have to continue to spray and pray. Instead, they can leverage real-world narratives, case studies, or even workshops that resonate directly with their ideal audience. This simplifies demonstrating how they differ from other financial services firms that attempt to be all things to all people. For instance, a financial advisor with specialized expertise in assisting early retirees can emphasize that in their web bios, slide decks, and lectures.

It’s just as important to redefine what makes a great selling advisor for each client segment. That is, listing skills, traits, or training areas that fit the needs of the ideal client. For instance, an advisor to doctors might require expertise related to loan repayment programs, whereas one for world travelers could emphasize global tax regulations or insurance for expats. Training can then focus on these points, ensuring each advisor develops deep expertise in the areas that count, ultimately leading to a more successful advisory practice.

The Sustainable Advisor Training Framework

The Susan Danzig Sustainable Advisor Training Framework helps financial advisors build strong client relationships, deliver great service, and prevent burnout. It’s flexible, measurable, and designed to develop long-term advisor effectiveness.

1. Mindset First

Establishing a sustainable practice as a financial advisor begins with mindset. Growth-minded advisors are more adaptable to change and more resilient in the face of setbacks. Self-reflection is crucial, assisting every advisor in identifying their strengths and opportunities to improve their client engagement. By fostering a constructive perspective on adversity, financial services firms can mitigate burnout risk and encourage sustainable involvement. Mindset training should be integrated into continuous coaching through real-world examples, like how to respond to a client’s objection or react to a market downturn. This consistent emphasis on mindset enables advisors to develop habits that sustain their mental health and professional satisfaction.

2. Niche Clarity

A well-defined niche enables financial advisors to attract the perfect clients. Workshops allow these advisors to explore market voids and their own passions, helping them double down on the areas where their expertise is most needed. For instance, a tech-savvy advisor can focus on first-time entrepreneurs, while resource guides outline niche opportunities and showcase successful advisors’ case studies, teaching them how to differentiate themselves in a crowded market.

3. Value Proposition

Advisors need to understand and articulate their worth in the financial services industry. Training can leverage templates and case studies to assist advisors in constructing succinct messages that demonstrate how they provide valuable financial advice. For instance, a case study may track a seasoned advisor who specializes in socially responsible investing and helps clients attain both their financial and ethical objectives. Advisors must train in explaining fees and illustrating how these correspond to the great service they provide.

4. Sustainable Marketing

Marketing that aligns with the financial advisor’s brand and goals is crucial. Digital tools, such as blog or tweet-sized updates, enable advisors to touch more prospective clients without experiencing financial advisor burnout. A sample content calendar might recommend monthly posts or quarterly newsletters based on client engagement. Checking marketing metrics, such as content reach or prospect conversion, allows successful advisors to adjust strategies and maintain effective outreach.

5. Intentional Networking

Building relationships is at the heart of long-term success for financial advisors. They should eschew quantity in favor of quality, focusing on qualitative, interesting relations with their client base and peers. Networking events, both in-person and virtual, may be organized around client interests or industry trends. Communication training refines listening and rapport-building skills, ensuring that advisors provide great service. A straightforward checklist, such as ‘ask open questions’ or ‘follow up within one week,’ keeps networking purposeful and effective.

Build Anti-Burnout Systems

Burnout is not an event;t, it grows incrementally in the daily grind. Training financial advisors to magnetically attract better clients is about building anti-burnout systems. What matters most is slicing the workload into obvious chunks. Begin by asking advisors to track tasks half hourly. Identify these activities by category: client calls, administrative work, planning, or breaks. When advisors see where hours go, they spot waste and can cut low-value tasks. If a daily log reveals that admin work consumes the majority of the day, leaders can redeploy support personnel to relieve the advisor for client-facing hours. This pivot aids every advisor in leveraging his or her strengths, cultivating their expertise, and endurance.

Workload management doesn’t end with tallying tasks. Two focused hours frequently trounce six hours of stop-and-start. Have advisors carve out time for deep work, financial plans, and client outreach, then put down phones and email. You get better results with this approach and reduce stress as well. Regular breaks aren’t just nice to have; they’re essential. Short walks, stretching, or quiet time between meetings aid mind reset. Advisors need to set a timer to stand up every hour and actually take a lunch break, not eat at their desk. Self-care is more than just breaks; writing down work goals each day, even small ones, can increase self-efficacy and combat burnout.

A solid peer network within the firm matters. Establish support channels, such as weekly team check-ins or shared digital boards, that allow advisors to exchange victories, discuss challenging cases, and collaborate. Once teams see where time is spent, they can intelligently shift work and assist each other. Advisors often wear many hats: they serve clients, sell new services, and run business tasks. It aids in dividing these tasks where possible and aligns them to each team member’s strengths. Build anti-burnout systems, such as mastery exercises, role play, case studies, and more, to make advisors feel prepared for every aspect of their work. Tracking workloads and setting transparent, equitable expectations is crucial. If you’re managing too many roles, modify your expectations or add assistance to control stress.

Corporate Training for Financial Advisory Firms

Leadership’s Critical Role

Leadership defines the manner in which financial advisors practice, how they develop, and how they serve their clients. In an industry where consumers expect more than stock picks, leadership must remain honest, transparent, and accessible. Successful advisors prescribe the moral tenor for both ethics and trust, forming the foundation of long-term customer loyalty. Good leaders ensure that clients feel listened to, valued, and cared about, which is crucial for maintaining a strong client base when there are so many other choices. Leadership’s critical role is to provide direction, assist teams with focus, and demonstrate how to prioritize the client.

Empower Leaders To Model Healthy Work-Life Balance For Their Teams

All day and all night, leaders can drive teams too hard. If a manager never rests, consultants might believe they need to work around the clock. This causes stress and burnout, damaging both team and client engagement. When leaders model working hours and taking time off, they demonstrate that balance isn’t merely permitted, it’s required. There’s nothing like leaders explaining how they approach work and rest to set a real example. Advisors who feel like they can take care of their own lives will do better work and build stronger client ties, ultimately becoming successful advisors.

Provide Leadership Training Focused On Supporting Advisor Development

It’s not about policy or statistics; it’s about how to lead with dignity and direct others during difficult moments. Effective training enables leaders to recognize when a financial advisor is bogged down or in need, equipping them with tools to help develop their client base, such as feedback, coaching, and praise. This training may teach leadership how to create trust and clarity of purpose, allowing advisors to focus on providing solid, truthful financial advice.

Encourage Open Communication Between Leadership And Advisors To Address Concerns

Open talk helps identify issues before they fester, which is crucial for financial advisors who aim to maintain a healthy client base. Leaders who facilitate making it easy to share thoughts or concerns foster trust within their teams. Scheduled check-ins or team meetings ensure advisors feel safe to speak up, ask questions, or share client feedback. If advisors can discuss their distress or effort, leaders can intervene prior to burnout. ‘Clear talk’ is useful for planning client meeting schedules and reviewing whether everyone is satisfied with how things operate.

Establish A Mentorship Program To Guide New Advisors Through Challenges

New advisors face numerous unknowns, and errors can lead to losing clients. A mentorship program pairs newer team members with seasoned advisors who have navigated the financial services landscape. Mentors provide valuable financial advice, teach how to approach difficult client conversations, and coach on effective strategies for decision-making. This support not only enables new advisors to learn faster but also fosters camaraderie and maintains a team focus on the same high expectations.

Measure What Truly Matters

When training financial advisors to win and retain ideal clients, it’s essential to look beyond the topline numbers and measure what truly matters to both trusted clients and advisors. Clients don’t abandon their advisors due to bad advice, weak relationships, or confusing fees; rather, they seek great service advisors who can adapt to their needs. Advisors aiming to differentiate themselves must understand the factors that drive retention and attrition, allowing them to refine their practices effectively.

A good starting point for successful advisors is defining practical means of measuring success through key performance indicators (KPIs). Client feedback is crucial for actual progress. Advisors should ask clients if the financial advice aligns with their goals, if communication is effective, and if they feel valued beyond just their investments. Some customers prefer monthly discussions, while others appreciate quarterly check-ins. By demystifying these preferences upfront, advisors can inspire confidence and avoid feelings of futility.

  1. Client Retention Rate: Count how many clients stay with the advisor year over year. High rates indicate strong relationships and good service.
  2. Net Promoter Score (NPS): Measures how likely clients are to recommend the advisor, which shows trust and satisfaction.
  3. Client Feedback Scores: Collect regular feedback on advice quality, communication, and service range. This provides a guide to where to improve.
  4. Time Spent On High-Impact Activities: Use a simple time audit to see how much time goes to activities that grow the business or add real value for clients.
  5. Revenue Per Ideal Client: Track what each ideal client brings in each year to see if the advisor is working with the right people.
  6. Advisor Satisfaction and Burnout Levels: Use rapid-fire surveys to monitor advisor stress, workload, and job satisfaction.

Advisors can stand out by offering more than just portfolio assistance. They should consider providing cash flow plans, tax tips, or guidance for business owners on retirement plans. Understanding who their ideal client is allows advisors to tailor their services accordingly instead of trying to appeal to everyone.

Periodic check-ins on these metrics and feedback ensure that firms keep their training and support aligned with client engagement. Advisors should focus on what works, scale successful strategies, and maintain a commitment to both client and advisor satisfaction.

The Future Of Advisor Development

The future of financial advisor growth is poised at the intersection of transformation and demand. With client perspectives changing, particularly as they near retirement, advisors must now see beyond the numbers. Many clients, 41%, either continue working or seek new employment after they retire. Future-ready advisors will have to assist with more life planning, not just money planning. This shift emphasizes the importance of providing comprehensive financial advice that encompasses all aspects of a client’s life.

Advisors can transition from fresh to proficient sales advisors quickly, typically within 3 to 12 months, only when the training is intelligent and continuous. To stay current in a rapidly evolving industry, advisory firms need to experiment with their training. That might involve increased peer learning, brief online courses, or experiential workshops. Firms must keep training fresh so advisors stay sharp and don’t burn out. Sustainable growth comes from consistent support and defined opportunities for skill development, not just a shove to get the sale.

Tech is a bigger part of the advisor role now. Leveraging tools such as generative AI can save you up to 3.3 hours a week, creating room for those more advanced client tasks. Advisors who identify which work to outsource, such as data entry and report generation, and leverage intelligent tools for monotonous tasks, will accomplish more with less anxiety. This means advisors can focus more time on things requiring their personal touch, such as client conversations and relationship building, which is crucial for maintaining a strong client base.

One giant leap is recognizing the need to plan better. Although just 43% of advisors have a business plan in writing, those who do experience 50% faster growth. It proves that measuring your goals and having clear ones changes things. Advisors should be educated to strategize, monitor progress, and pivot. That way, they can stay ahead of changes in client demands and the industry, ensuring they remain effective in their financial services practice.

Specialization is another trend. Advisors who niche, say tech workers or expats, convert and grow more. That implies future training ought to assist advisors in identifying their niche and learning the skills required for that space. Meanwhile, cost containment is crucial. Growth-minded advisors invest approximately 7% of their revenue to attract new clients, less than the rest, demonstrating the importance of intelligent, targeted marketing.

Final Remarks

At Susan Danzig, we believe that training financial advisors for long-term success means focusing on real skills and real support. Smart goals, consistent training, and robust systems help advisors thrive. Great leaders create room for candid conversations and provide steady, actionable feedback. Measure improvement with real numbers, not just anecdotes, and stay open to fresh ideas and innovative tools. Top-performing teams know what works, fix what doesn’t, and celebrate progress.

To attract more ideal clients, help advisors build confidence, maintain healthy work habits, and grow sustainably. Every team can start small, try a new habit, test a new strategy, and seek feedback. Continue learning with Susan Danzig. Share what’s working for your firm or reach out to start a conversation about what’s next.

Frequently Asked Questions

1. How Can Financial Advisors Define Their “Ideal Client”?

Be very specific about the type of prospective clients you serve best, including their traits, needs, and values. Utilize data and feedback to polish this profile for effective client engagement and outcomes.

2. What Is A Sustainable Advisor Training Framework?

A sustainable framework for financial advisors focuses on long-term skills, continuous learning, and well-being, providing actionable training and mentorship to prevent financial advisor burnout.

3. How Do Anti-Burnout Systems Help Financial Advisors?

They help you enforce a healthy work-life balance, maintain boundaries, and take regular breaks! This support keeps financial advisors inspired and energized to serve more prospective clients.

4. How Can Firms Prepare Advisors For Future Client Needs?

Providing continuous education and fostering flexibility helps financial advisors stay relevant, ensuring they can meet client engagement needs and implement effective strategies.

5. How Does Training Reduce Advisor Burnout?

Good training for financial advisors teaches time management, self-care, and effective strategies for stress reduction, ensuring they do not experience burnout.

Learn More About Coaching Packages

Ready to help your team attract more ideal clients without the burnout? At Susan Danzig, we offer personalized coaching packages designed to strengthen your advisors’ skills, clarify your firm’s message, and build systems that support long-term growth. Whether you’re looking to refine your niche, create stronger client connections, or train your team for measurable results, we’re here to help. Learn more about our coaching packages and discover how we can help your advisors thrive with clarity, confidence, and purpose. Connect with us today.

How To Train Your Financial Advisors To Attract More Ideal Clients – Without Burning Out

At Susan Danzig, we help financial advisors learn how to attract more ideal clients without burning out by focusing on people skills, time use, and sustainable systems. Advisors who listen well, establish healthy boundaries, and apply intelligent technology tend to gain client confidence and maintain their practice with ease. Providing regular feedback, sharing real-life stories, and encouraging advisors to celebrate their victories all contribute to enhanced team development and morale. Training is most effective when it blends real-world experience with collaborative learning, so advisors develop habits that last. By leveraging these fundamentals, Susan Danzig helps firms and advisors attract ideal clients while keeping burnout low.

Key Takeaways

  • By knowing exactly what ideal clients look like and require, financial advisors can customize their offerings, focus their promotion, and provide more targeted engagement even in different markets.
  • Instead, by embracing a sustainable training framework that combines both technical and interpersonal skills and structured feedback mechanisms, you foster long-term advisor growth and alignment with organizational goals.
  • Instilling a growth mindset and self-reflection in advisors promotes resilience, prevents burnout, and nurtures lifelong learning.
  • By bringing clarity around niche markets and a clear value proposition, you help advisors attract and retain ideal clients, those best suited to their strengths, for more fulfilling and effective relationships.
  • By developing sustainable marketing and intentional networking strategies backed by digital tools, regular communication, and relationship-building experts, advisors extend their reach without sacrificing themselves.
  • Leadership needs to take the lead in advisor well-being, setting the tone with example, modeling sustainable work-life balance, and providing opportunities for personal and professional development, and routinely measuring the KPIs that ensure advisors stay happy and successful.
Corporate Training for Financial Advisory Firms

Redefine The “Ideal Client”

Training financial advisors to bring in more ideal clients begins with a solid understanding of who those clients really are. At Susan Danzig, we emphasize the importance of aligning the right financial advice to the right person so advisors spend their time and talents where they work best. Certain advisors flourish assisting doctors with student loans, while others excel in helping pre-retirees prepare for early retirement and travel. Once advisors know these details, they can tailor their services, speak directly to those clients’ needs, and avoid mismatched relationships.

Knowing your ideal client is about more than just numbers or job titles. It’s about understanding what drives these customers, what fears they have, and what economic challenges they face. A doctor with a big student loan balance may need tips for how to pay off debt while building a practice. A friend flirting with retirement might require advice on income planning, health insurance decisions, or smart Roth conversions. Advisors who dig deep into a particular group can bring more to the table. They know more hacks, resources, and alternatives that suit those individuals best. That results in more trust and greater outcomes for both parties, enhancing the overall client engagement experience.

With a well-defined profile of the client they desire, advisors can adjust their marketing and outreach accordingly. They don’t have to continue to spray and pray. Instead, they can leverage real-world narratives, case studies, or even workshops that resonate directly with their ideal audience. This simplifies demonstrating how they differ from other financial services firms that attempt to be all things to all people. For instance, a financial advisor with specialized expertise in assisting early retirees can emphasize that in their web bios, slide decks, and lectures.

It’s just as important to redefine what makes a great selling advisor for each client segment. That is, listing skills, traits, or training areas that fit the needs of the ideal client. For instance, an advisor to doctors might require expertise related to loan repayment programs, whereas one for world travelers could emphasize global tax regulations or insurance for expats. Training can then focus on these points, ensuring each advisor develops deep expertise in the areas that count, ultimately leading to a more successful advisory practice.

The Sustainable Advisor Training Framework

The Susan Danzig Sustainable Advisor Training Framework helps financial advisors build strong client relationships, deliver great service, and prevent burnout. It’s flexible, measurable, and designed to develop long-term advisor effectiveness.

1. Mindset First

Establishing a sustainable practice as a financial advisor begins with mindset. Growth-minded advisors are more adaptable to change and more resilient in the face of setbacks. Self-reflection is crucial, assisting every advisor in identifying their strengths and opportunities to improve their client engagement. By fostering a constructive perspective on adversity, financial services firms can mitigate burnout risk and encourage sustainable involvement. Mindset training should be integrated into continuous coaching through real-world examples, like how to respond to a client’s objection or react to a market downturn. This consistent emphasis on mindset enables advisors to develop habits that sustain their mental health and professional satisfaction.

2. Niche Clarity

A well-defined niche enables financial advisors to attract the perfect clients. Workshops allow these advisors to explore market voids and their own passions, helping them double down on the areas where their expertise is most needed. For instance, a tech-savvy advisor can focus on first-time entrepreneurs, while resource guides outline niche opportunities and showcase successful advisors’ case studies, teaching them how to differentiate themselves in a crowded market.

3. Value Proposition

Advisors need to understand and articulate their worth in the financial services industry. Training can leverage templates and case studies to assist advisors in constructing succinct messages that demonstrate how they provide valuable financial advice. For instance, a case study may track a seasoned advisor who specializes in socially responsible investing and helps clients attain both their financial and ethical objectives. Advisors must train in explaining fees and illustrating how these correspond to the great service they provide.

4. Sustainable Marketing

Marketing that aligns with the financial advisor’s brand and goals is crucial. Digital tools, such as blog or tweet-sized updates, enable advisors to touch more prospective clients without experiencing financial advisor burnout. A sample content calendar might recommend monthly posts or quarterly newsletters based on client engagement. Checking marketing metrics, such as content reach or prospect conversion, allows successful advisors to adjust strategies and maintain effective outreach.

5. Intentional Networking

Building relationships is at the heart of long-term success for financial advisors. They should eschew quantity in favor of quality, focusing on qualitative, interesting relations with their client base and peers. Networking events, both in-person and virtual, may be organized around client interests or industry trends. Communication training refines listening and rapport-building skills, ensuring that advisors provide great service. A straightforward checklist, such as ‘ask open questions’ or ‘follow up within one week,’ keeps networking purposeful and effective.

Build Anti-Burnout Systems

Burnout is not an event;t, it grows incrementally in the daily grind. Training financial advisors to magnetically attract better clients is about building anti-burnout systems. What matters most is slicing the workload into obvious chunks. Begin by asking advisors to track tasks half hourly. Identify these activities by category: client calls, administrative work, planning, or breaks. When advisors see where hours go, they spot waste and can cut low-value tasks. If a daily log reveals that admin work consumes the majority of the day, leaders can redeploy support personnel to relieve the advisor for client-facing hours. This pivot aids every advisor in leveraging his or her strengths, cultivating their expertise, and endurance.

Workload management doesn’t end with tallying tasks. Two focused hours frequently trounce six hours of stop-and-start. Have advisors carve out time for deep work, financial plans, and client outreach, then put down phones and email. You get better results with this approach and reduce stress as well. Regular breaks aren’t just nice to have; they’re essential. Short walks, stretching, or quiet time between meetings aid mind reset. Advisors need to set a timer to stand up every hour and actually take a lunch break, not eat at their desk. Self-care is more than just breaks; writing down work goals each day, even small ones, can increase self-efficacy and combat burnout.

A solid peer network within the firm matters. Establish support channels, such as weekly team check-ins or shared digital boards, that allow advisors to exchange victories, discuss challenging cases, and collaborate. Once teams see where time is spent, they can intelligently shift work and assist each other. Advisors often wear many hats: they serve clients, sell new services, and run business tasks. It aids in dividing these tasks where possible and aligns them to each team member’s strengths. Build anti-burnout systems, such as mastery exercises, role play, case studies, and more, to make advisors feel prepared for every aspect of their work. Tracking workloads and setting transparent, equitable expectations is crucial. If you’re managing too many roles, modify your expectations or add assistance to control stress.

Corporate Training for Financial Advisory Firms

Leadership’s Critical Role

Leadership defines the manner in which financial advisors practice, how they develop, and how they serve their clients. In an industry where consumers expect more than stock picks, leadership must remain honest, transparent, and accessible. Successful advisors prescribe the moral tenor for both ethics and trust, forming the foundation of long-term customer loyalty. Good leaders ensure that clients feel listened to, valued, and cared about, which is crucial for maintaining a strong client base when there are so many other choices. Leadership’s critical role is to provide direction, assist teams with focus, and demonstrate how to prioritize the client.

Empower Leaders To Model Healthy Work-Life Balance For Their Teams

All day and all night, leaders can drive teams too hard. If a manager never rests, consultants might believe they need to work around the clock. This causes stress and burnout, damaging both team and client engagement. When leaders model working hours and taking time off, they demonstrate that balance isn’t merely permitted, it’s required. There’s nothing like leaders explaining how they approach work and rest to set a real example. Advisors who feel like they can take care of their own lives will do better work and build stronger client ties, ultimately becoming successful advisors.

Provide Leadership Training Focused On Supporting Advisor Development

It’s not about policy or statistics; it’s about how to lead with dignity and direct others during difficult moments. Effective training enables leaders to recognize when a financial advisor is bogged down or in need, equipping them with tools to help develop their client base, such as feedback, coaching, and praise. This training may teach leadership how to create trust and clarity of purpose, allowing advisors to focus on providing solid, truthful financial advice.

Encourage Open Communication Between Leadership And Advisors To Address Concerns

Open talk helps identify issues before they fester, which is crucial for financial advisors who aim to maintain a healthy client base. Leaders who facilitate making it easy to share thoughts or concerns foster trust within their teams. Scheduled check-ins or team meetings ensure advisors feel safe to speak up, ask questions, or share client feedback. If advisors can discuss their distress or effort, leaders can intervene prior to burnout. ‘Clear talk’ is useful for planning client meeting schedules and reviewing whether everyone is satisfied with how things operate.

Establish A Mentorship Program To Guide New Advisors Through Challenges

New advisors face numerous unknowns, and errors can lead to losing clients. A mentorship program pairs newer team members with seasoned advisors who have navigated the financial services landscape. Mentors provide valuable financial advice, teach how to approach difficult client conversations, and coach on effective strategies for decision-making. This support not only enables new advisors to learn faster but also fosters camaraderie and maintains a team focus on the same high expectations.

Measure What Truly Matters

When training financial advisors to win and retain ideal clients, it’s essential to look beyond the topline numbers and measure what truly matters to both trusted clients and advisors. Clients don’t abandon their advisors due to bad advice, weak relationships, or confusing fees; rather, they seek great service advisors who can adapt to their needs. Advisors aiming to differentiate themselves must understand the factors that drive retention and attrition, allowing them to refine their practices effectively.

A good starting point for successful advisors is defining practical means of measuring success through key performance indicators (KPIs). Client feedback is crucial for actual progress. Advisors should ask clients if the financial advice aligns with their goals, if communication is effective, and if they feel valued beyond just their investments. Some customers prefer monthly discussions, while others appreciate quarterly check-ins. By demystifying these preferences upfront, advisors can inspire confidence and avoid feelings of futility.

  1. Client Retention Rate: Count how many clients stay with the advisor year over year. High rates indicate strong relationships and good service.
  2. Net Promoter Score (NPS): Measures how likely clients are to recommend the advisor, which shows trust and satisfaction.
  3. Client Feedback Scores: Collect regular feedback on advice quality, communication, and service range. This provides a guide to where to improve.
  4. Time Spent On High-Impact Activities: Use a simple time audit to see how much time goes to activities that grow the business or add real value for clients.
  5. Revenue Per Ideal Client: Track what each ideal client brings in each year to see if the advisor is working with the right people.
  6. Advisor Satisfaction and Burnout Levels: Use rapid-fire surveys to monitor advisor stress, workload, and job satisfaction.

Advisors can stand out by offering more than just portfolio assistance. They should consider providing cash flow plans, tax tips, or guidance for business owners on retirement plans. Understanding who their ideal client is allows advisors to tailor their services accordingly instead of trying to appeal to everyone.

Periodic check-ins on these metrics and feedback ensure that firms keep their training and support aligned with client engagement. Advisors should focus on what works, scale successful strategies, and maintain a commitment to both client and advisor satisfaction.

The Future Of Advisor Development

The future of financial advisor growth is poised at the intersection of transformation and demand. With client perspectives changing, particularly as they near retirement, advisors must now see beyond the numbers. Many clients, 41%, either continue working or seek new employment after they retire. Future-ready advisors will have to assist with more life planning, not just money planning. This shift emphasizes the importance of providing comprehensive financial advice that encompasses all aspects of a client’s life.

Advisors can transition from fresh to proficient sales advisors quickly, typically within 3 to 12 months, only when the training is intelligent and continuous. To stay current in a rapidly evolving industry, advisory firms need to experiment with their training. That might involve increased peer learning, brief online courses, or experiential workshops. Firms must keep training fresh so advisors stay sharp and don’t burn out. Sustainable growth comes from consistent support and defined opportunities for skill development, not just a shove to get the sale.

Tech is a bigger part of the advisor role now. Leveraging tools such as generative AI can save you up to 3.3 hours a week, creating room for those more advanced client tasks. Advisors who identify which work to outsource, such as data entry and report generation, and leverage intelligent tools for monotonous tasks, will accomplish more with less anxiety. This means advisors can focus more time on things requiring their personal touch, such as client conversations and relationship building, which is crucial for maintaining a strong client base.

One giant leap is recognizing the need to plan better. Although just 43% of advisors have a business plan in writing, those who do experience 50% faster growth. It proves that measuring your goals and having clear ones changes things. Advisors should be educated to strategize, monitor progress, and pivot. That way, they can stay ahead of changes in client demands and the industry, ensuring they remain effective in their financial services practice.

Specialization is another trend. Advisors who niche, say tech workers or expats, convert and grow more. That implies future training ought to assist advisors in identifying their niche and learning the skills required for that space. Meanwhile, cost containment is crucial. Growth-minded advisors invest approximately 7% of their revenue to attract new clients, less than the rest, demonstrating the importance of intelligent, targeted marketing.

Final Remarks

At Susan Danzig, we believe that training financial advisors for long-term success means focusing on real skills and real support. Smart goals, consistent training, and robust systems help advisors thrive. Great leaders create room for candid conversations and provide steady, actionable feedback. Measure improvement with real numbers, not just anecdotes, and stay open to fresh ideas and innovative tools. Top-performing teams know what works, fix what doesn’t, and celebrate progress.

To attract more ideal clients, help advisors build confidence, maintain healthy work habits, and grow sustainably. Every team can start small, try a new habit, test a new strategy, and seek feedback. Continue learning with Susan Danzig. Share what’s working for your firm or reach out to start a conversation about what’s next.

Frequently Asked Questions

1. How Can Financial Advisors Define Their “Ideal Client”?

Be very specific about the type of prospective clients you serve best, including their traits, needs, and values. Utilize data and feedback to polish this profile for effective client engagement and outcomes.

2. What Is A Sustainable Advisor Training Framework?

A sustainable framework for financial advisors focuses on long-term skills, continuous learning, and well-being, providing actionable training and mentorship to prevent financial advisor burnout.

3. How Do Anti-Burnout Systems Help Financial Advisors?

They help you enforce a healthy work-life balance, maintain boundaries, and take regular breaks! This support keeps financial advisors inspired and energized to serve more prospective clients.

4. How Can Firms Prepare Advisors For Future Client Needs?

Providing continuous education and fostering flexibility helps financial advisors stay relevant, ensuring they can meet client engagement needs and implement effective strategies.

5. How Does Training Reduce Advisor Burnout?

Good training for financial advisors teaches time management, self-care, and effective strategies for stress reduction, ensuring they do not experience burnout.

Learn More About Coaching Packages

Ready to help your team attract more ideal clients without the burnout? At Susan Danzig, we offer personalized coaching packages designed to strengthen your advisors’ skills, clarify your firm’s message, and build systems that support long-term growth. Whether you’re looking to refine your niche, create stronger client connections, or train your team for measurable results, we’re here to help. Learn more about our coaching packages and discover how we can help your advisors thrive with clarity, confidence, and purpose. Connect with us today.

The Top 7 Reasons Financial Advisory Firms Struggle To Scale – And How Training Fixes Them

The top 7 reasons financial advisory firms struggle to scale tend to connect to gaps in skills, processes, and team knowledge. Slow onboarding, poor adoption of technology tools, inefficient workflows, and no client trust are the common culprits. Many have trouble with compliance, bad data utilization, and bottlenecks in team scaling.

At Susan Danzig, training helps fix these issues by developing genuine capabilities, establishing defined processes, and ensuring teams can optimally leverage new tools. Great training fosters robust client relationships, ensures teams are current on regulations, and keeps operations efficient. To demonstrate how training assists, the following sections dissect each challenge and provide practical methods to apply training for consistent growth and improved outcomes.

Key Takeaways

  • Leadership bottlenecks, inconsistent client experiences, and stagnant advisor skills are the top reasons financial advisory firms can’t scale. Training fixes these issues.
  • By standardizing client service protocols and investing in ongoing advisor development, firms can provide consistent, high-quality experiences that enhance retention and create growth opportunities.
  • Operational efficiency and technology both increase efficiency and profitability. Employee training allows for their maximum impact by promoting best practices.
  • A forward-thinking business development approach, reinforced by ongoing training and coaching, gives advisors the ability to scale their practices and respond to market evolutions.
  • By investing in great training, you neutralize the hidden costs associated with stagnation, such as potential talent loss, reduced firm value, and principal burnout, protecting the firm’s longevity.
  • After a regular review, customization, and reinforcement of training content, together with strong outcome measurement, keep the learning initiatives relevant and return measurable returns for financial advisory firms worldwide.
Corporate Training for Financial Advisory Firms

Why Firms Fail To Scale

Financial advisory firms face specific obstacles to growth, including leadership, customer relations, and talent acquisition. These financial challenges can stall progress and impact retention if not managed effectively, hindering the success of financial advisors.

1. Leadership Bottlenecks

Leadership bottlenecks delay the speed at which firms decide and respond, particularly in the financial advisory industry. When leaders hold decisions tight, teams lose velocity, and morale sinks. Too often, firms suffer from an absence of open discussions among executives, which keeps risk-taking and collaboration low. Without solid leadership training from Susan Danzig, such managers struggle to manage growth and establish trust, essential for financial advisor success. Succession planning is absent in many firms, risking havoc when leaders depart, especially urgent when advisor attrition is high, as just 15 to 16 percent of financial advisors remain at year five.

2. Inconsistent Client Experience

Client service varies significantly among financial advisors, leading to some customers experiencing excellent service while others feel frustrated. Without a defined process to guide prospect conversations, advisory firms miss opportunities for consistent referrals and enduring loyalty. New advisors may sometimes neglect training in building trust and understanding personality types, which undermines effective fact-finding. As a result, forty-four percent of advisors give up after the initial attempt. Leveraging tech tools and Susan Danzig’s client experience training can enhance retention and satisfaction.

3. Stagnant Advisor Skills

Advisors who don’t stay on top of their financial expertise get left behind. As the financial landscape shifts, so do clients’ needs. If advisory firms don’t train their financial advisors on new laws, products, or trends, they can’t provide optimal guidance. Few firms measure advisor skill gaps or conduct ongoing workshops, and many overlook the importance of matching new hires with mentors, a low-cost method that Susan Danzig promotes to enhance advisor success and confidence.

4. Inefficient Operations

Others operate with legacy or clunky systems, leading to diminished margins and wasted employee hours. Many financial advisory firms fail to leverage technology to automate repetitive tasks or analyze workflows effectively. Whether teams are trained on pristine data habits or financial reporting, errors can sneak in and disrupt the pace. Susan Danzig’s operational strategy training addresses these gaps to streamline performance.

5. Reactive Business Development

Too many financial advisory firms pursue leads only once business falls off, lacking a strategy to seek new customers or identify trends in their infancy. Poor prospecting is a top reason for financial advisor failure. With Susan Danzig’s business development programs, advisors learn proactive prospecting education that builds confidence, consistency, and stronger pipelines.

6. Poor Technology Adoption

Firms that are slow to adopt tech fall behind quickly in the competitive financial advisory industry. Few ever audit which tools truly assist or educate financial advisors on how to use them effectively. If financial professionals are afraid of new tech or don’t see the point, they won’t use it, making it difficult to serve clients well and wasting money on unused infrastructure. Susan Danzig helps teams integrate technology confidently into daily workflows for maximum ROI.

7. A Missing Growth Culture

Growth in the financial advisory industry requires a team mentality. If firms don’t set goals or reward smart risks, their advisors stick to what’s safe, and change stalls. Without investing in learning or celebrating wins, advisory firms can’t build the grit for long-term success. Susan Danzig’s programs instill a growth culture by aligning development, recognition, and performance goals across the organization.

The Training Solution

A strong training solution can solve most of the universal obstacles holding financial advisory firms back from scaling. Targeted, measured training ensures that everyone from senior leaders to new advisors possesses the financial expertise and skills required for sustainable growth. By tying these efforts to business objectives, deploying a variety of learning strategies, and embracing continuous feedback, companies can pivot and prosper even as the financial landscape changes.

Strategic Leadership

Leadership development is at the heart of our advisory firm’s growth engine. Leaders who take advantage of emotional intelligence training are better able to lead their teams, manage stress, and defuse tension. By focusing on leadership training for new advisors, we provide long-term assurance and accountability. This approach strengthens a results-oriented culture that values performance and ethics equally, ensuring financial advisor success.

Scalable Processes

Advisory firms can achieve financial advisor success by ensuring that their internal processes provide leeway and repeatability. Capturing your best practices in standard operating procedures can minimize mistakes and simplify training. Teaching staff scalable practices ensures that everyone takes the same actions when onboarding a client or working on trades. By transforming large projects into actionable tasks, these teams can prevent themselves from getting overwhelmed. It is crucial to review and update these processes as your business and your clients’ financial goals change, so that efficiency is not sacrificed to growth.

The Advisor Development

  • Advanced financial planning methods
  • Client relationship building
  • Industry conference attendance
  • Mentorship and skill sharing

Continuous training provides financial advisors with the resources to thrive beyond technical expertise. Advocating networking and attendance at industry events broadens perspectives, while a mentorship system enables new advisors to learn from successful advisors, accelerating skill development and minimizing errors.

Client Management

Client happiness depends on those first couple of months. Coaches need to train financial advisors to communicate consistently and follow up quickly, as studies indicate that most revenue slips through the cracks due to a lack of persistent outreach. Dividing customers guarantees treatment fits every need. A CRM tracks every client touchpoint, simplifying communication and allowing advisors to customize their touch. When advisory firms track touchpoints and polish service standards, loyalty and referrals increase, particularly if backed by continuous client input.

Corporate Training for Financial Advisory Firms

The Hidden Cost Of Stagnation

The stagnation in financial advisory firms isn’t merely about sluggish expansion; it also involves hidden financial challenges that nibble away at long-term profits and the firm’s future. When firms cease growing, they risk losing their top advisors, witnessing their valuation plummet, and exhausting their leadership. These costs extend far beyond missed financial goals and can jeopardize the advisory business itself.

Talent Attrition

There’s high turnover in the financial advisory industry, with over 90% of financial advisors quitting during their initial three years. Many leave because they feel their financial expertise isn’t advancing or their contributions aren’t valued. Others struggle to apply core concepts such as asset allocation or portfolio theory to practical activities, and this skills gap can make the work feel crushing.

An absence of obvious growth trajectories and a poor culture of learning is pushing employees out. Without a robust career development plan, successful advisors look elsewhere. This turnover isn’t only financial, it’s about losing the confidence and experience that clients appreciate.

Companies can decelerate this churn by providing training that connects learning with actual business demands. Competitive pay does this, but so does a culture that respects everyone’s contribution, encourages mental wellness, and maintains the dialogue in the advisory firm.

Diminished Firm Value

When firms lag, their value sinks. Dinosaur cultures, such as eschewing new digital tools or neglecting to refresh prospecting strategies, damage the firm’s external reputation. In a world where clients expect frictionless digital service and intelligent personal guidance, a lapse in pace taints the firm’s brand and value.

The Hidden Cost of Stagnation. For example, advisers who don’t refresh their prospecting approach or don’t ‘Fact Find’ with clients will leave half their income on the table. When you’re not innovating, you can drive clients to competitors with cooler tools and cleverer service.

Leaders must drive continuous learning, improved digital capabilities, and active client feedback. These measures keep the firm fresh and increase both client satisfaction and firm value.

Principal Burnout

Company leaders typically deal with overwork and burnout. Burnout is not uncommon, and when it occurs, it leads to bad decisions and low morale throughout the team.

Wellness programs and coaching can help leaders manage stress and stay focused. A work-life balance drive combined with explicit backing for mental health can keep principals efficient and optimistic.

Designing Effective Training

Financial advisory firms encounter unique growth challenges in the financial advisory industry. Actionable training can combat these through a combination of process documentation, skills training, and continuous refinement. Effective training begins by diagnosing what works in financial management and builds on strengths while engaging all stakeholders.

Assess Needs

Firms should start with surveys and one-on-one interviews to gather input from staff and leadership, which is essential for identifying financial challenges and revealing where confusion or inefficiency lurks. By analyzing key performance metrics, such as client retention rates, turnaround time, and error rates, firms can pinpoint areas where financial expertise is lacking. This analysis allows the firms to consider which training will be the most valuable, whether it’s client onboarding or portfolio management. Prioritizing these issues is key because not every problem requires immediate addressing, and involving financial advisors in this process ensures that the training provided is effectively utilized.

Customize Content

Designing Effective Training for financial advisors requires companies to tackle problems specific to the advisory industry, such as reconciling compliance with customized client solutions. Real-world case studies introduce relevance, allowing trainees to witness theory in action. Materials should reflect industry standards and trends, including innovations in financial reporting or portfolio rebalancing. Ensuring that subject matter experts create the content guarantees that it’s both accurate and useful. For instance, a process could be recorded to template some 80 percent of a job, leaving 20 percent for the ‘special sauce’, customization for each client. This combination of standardization and flexibility allows successful advisors to improve their process without sacrificing client service.

Implement And Reinforce

Checklist for reinforcement:

  • Plan for frequent training follow-ups. Each should involve reviewing important concepts and talking through how they manifest in day-to-day work, such as picking investments and speaking to clients.
  • Track staff advancements via statistics and face-to-face communication. Provide group and individual feedback to focus development.
  • Foster a learning environment. That doesn’t mean just repeated training, it means revisiting and innovating on one documented process after another, always looking for leaner ways of working.
  • Build technology for repeatable decisions, such as trading or rebalancing, and automate routine work to make room for higher-value tasks.

Measuring Training ROI

Training ROI is a crucial measurement for financial advisory firms seeking to scale efficiently. It offers a transparent view into whether training investments genuinely enhance outcomes. By tracking both numbers and human feedback, firms can assess if financial advisors are improving, if clients are more satisfied, and if the firm is experiencing growth. Given the high overhead in the financial advisory industry, any training must yield returns, or it could hinder profitability. Here’s a table of typical impact measures, learner outcomes, and customer satisfaction post-learning.

Metric

Before Training

After Training

Change

Advisor Revenue (USD)

$8,000

$10,500

+31%

Client Retention (%)

70%

82%

+12%

Satisfaction Score

3.1/5

4.6/5%

+1.5 %

Completion Rate (%)

92%

97% 

5%

Companies need to Measure Training ROI. Firms need to measure advisor performance, retention, and revenue to determine whether training is effective. Changes in these metrics, even minor ones, can translate into actual gains. If a training program costs $6,000 and brings $5,000 in gains, the ROI is negative. The calculation is as follows: five thousand dollars minus six thousand dollars divided by six thousand dollars multiplied by one hundred equals negative sixteen point sixty-six percent. A positive ROI, particularly over three hundred percent, is a sure indication that the investment made an impact. Be sure to account for direct costs, such as course fees, and indirect ones, such as time invested in learning.

Key Performance Indicators

KPIs provide a straightforward method to quantify the effect. The following table separates advisor performance and client engagement before and after training.

KPI

Pre-Training

Post-Training

Δ

Avg. Client Meetings

8/month

13/month

+5

Upsell Rate (%)

18%

27%

+9%

Cross-Sell Ratio

0.9

1.3

+0.4

Following these KPIs post-training assists in identifying strengths and gaps. Companies might notice that meeting frequency or upsell rates soar post-training, indicating immediate returns. Sending KPI results to team members and leaders allows everyone to see what’s working and where additional training is required.

Qualitative Feedback

Direct feedback from trainees is critical to the statistics. Surveys and interviews assist in collecting frank feedback on what succeeded and what failed. Attendees could mention that a session was too elementary or that role-play improved their pitching. This feedback indicates what parts of the training stick and which do not.

Even something as simple as mining comments to see if people say they feel more confident or if clients feel a difference can help. If they say, “I used the new script and closed two deals,” that’s a pretty good indicator that training made a difference. Insights from these sessions assist in molding upcoming courses, so each iteration improves.

Long-Term Impact

Long-term tracking is key to knowing if training sticks. If advisor performance remains high and client relationships continue to deepen, the training works. Culture changes, such as increased sharing or accelerated skill development, can be observed over time, not just immediately after training concludes.

Evaluating these big-picture gains, like improved employee retention or reduced expenses, is crucial. Putting a victory banner around a tale like this, where one team doubled client retention due to training, can demonstrate tangible worth to everyone.

Beyond The Training Room

Training is a great kick-off for aspiring financial advisors. Real growth occurs when learning becomes a regular part of work. Many financial professionals frequently abandon the profession because the leap from the training room to practice is tough. They often struggle to find clients, build trust, and manage their business effectively. The business’s brutal burn rate, with 90% leaving within three years, demonstrates what a hard road this is. Advisors require more than quick workshops to stay on target and achieve financial advisor success.

A culture of growth helps both new and veteran advisors manage the pressure associated with the financial advisory industry. Companies that appreciate training beyond the classroom gain more value. When teams get together regularly, share what works, and learn from each other, they develop their financial expertise more quickly. Peer-to-peer learning, whether through shadowing a seasoned financial planner or engaging in group discussions, allows new hires to experience real problems and solutions. This helps bridge the transition from classroom instruction to real work. For instance, a new advisor could pick up more effective ways to acquire clients or conduct difficult conversations from a peer who has navigated these challenges successfully.

‘Check-ins’ and coaching keep skills sharp and relevant. These sessions capture opportunities early and allow financial advisors to discuss actual cases with coaches. They can request feedback on prospecting, which is one of the hardest parts of the job. A lot of advisors quit because they feel they can’t help clients or are being forced to sell products they don’t believe in. Coaching can help them construct a process for selecting investments they trust, making their day-to-day work less stressful and more authentic.

Like anything else, tools and tech make it easier for advisors to continue learning and improving their financial advisory services. Online communities allow them to discuss cases, swap advice, or engage in worldwide forums. Digital resources simplify tracking client needs and provide immediate feedback. In those initial months of a client relationship, this support can really make a difference. Advisors with a defined, replicable process to deliver financial advice spend less time on administrative tasks and more time on scaling their advisory business.

Final Remarks

Scaling up feels hard for financial advisory firms. Big culprits like old habits, weak teamwork, and skills gaps derail true growth. Susan Danzig helps teams pick up new tech, refine key skills, and escape the rut of slow growth. These obvious takeaways demonstrate immediate victories: quicker client assistance, higher quality work, and increased profitability.

Effective training only happens if leaders support it and continue to measure what works. Steady effort is what it takes, not one-off classes. New skills help firms keep up in rapid markets. To build a team that grows strong, make learning part of the job.

Jump into the discussion below and share what training has made the biggest impact in your firm. With Susan Danzig, growth is always a measurable outcome.

Frequently Asked Questions

1. What Are The Main Reasons Financial Advisory Firms Struggle To Scale?

In the top 7 reasons financial advisory firms can’t scale and how training fixes them, training enhances financial expertise, develops skills, consistency, and confidence for financial advisors.

2. How Does Employee Training Help Advisory Firms Grow?

Training provides your staff, including financial advisors, with the skills they need, enhances client service, and increases productivity. Well-trained teams can serve more clients, respond to financial challenges, and maintain predictable outcomes, making scaling a lot simpler.

3. What Is The Hidden Cost Of Not Investing In Training?

Without training, firms incur greater employee turnover, lost clients, and growth opportunities. This results in higher expenses and constrains the firm’s sustainable growth.

4. How Can Firms Design Effective Training Programs?

They address all seven of the top reasons financial advisory firms fail to scale, and here’s how training enhances financial advisor success. These strategies should be customized to the firm’s requirements and continually refreshed to remain pertinent.

5. How Do You Measure The Return On Investment (ROI) For Training?

Return on investment for training is measured by monitoring enhancements in staff effectiveness, client contentment, and company expansion, as well as metrics like client retention and revenue growth in the financial advisory industry.

Let’s Build Your Firm’s Growth Plan Together

Scaling a financial advisory firm takes more than ambition; it requires a focused strategy, consistent training, and a team that knows how to execute. At Susan Danzig, we specialize in helping firms like yours overcome bottlenecks, strengthen leadership, and build sustainable systems for growth. Whether your challenge is onboarding, client experience, or business development, our tailored training plans are designed to turn potential into measurable progress.

Contact us today to discuss a tailored training plan that aligns with your firm’s goals and equips your advisors with the skills to thrive. Let’s create a structure for consistent growth, confident leadership, and long-term success. Schedule a consultation with our team now.

Why Financial Advisory Firms Need A 90-Day Marketing Plan At The Team Level

At Susan Danzig, we help financial advisory firms create practical 90-day marketing plans that keep teams focused, accountable, and agile. A short plan allows teams to understand what works and what doesn’t, so they can better utilize their time and money. Teams can experiment with concepts, connect with more individuals, and collaborate with less ambiguity. In an industry where regulations and client needs change frequently, a 90-day plan provides a method to remain agile and identify emerging trends. Powerhouse firms with solid team planning can move much faster than those on the old slow track. In the sections below, we discuss how a 90-day plan works and why it’s a good fit for the reality of financial advisory teams.

Key Takeaways

  • A 90-day marketing plan at the team level makes financial advisory firms agile, able to react quickly to changes in the industry and their clients’ needs with informed, data-driven decisions.
  • Well-defined, just enough, short-term planning fosters clear accountability. Everyone knows what they’re responsible for and is held accountable to specific performance metrics.
  • The key to success is having focused, achievable milestones along the way.
  • By focusing on big-impact marketing activities and strategically allocating resources, you can maximize your results. Regular review processes allow you to refine your approach for optimum effectiveness.
  • By standardizing compliance protocols and documenting marketing processes, firms minimize regulatory risks. This helps them consistently deliver client communications that are compliant and trustworthy across channels.
  • By tracking metrics like lead velocity, client acquisition, and engagement rates, the firm can continuously optimize its efforts and tie marketing activities to tangible value.
Corporate Training for Financial Advisory Firms

Why A 90-Day Marketing Plan

A 90-day marketing plan serves as an effective marketing strategy for financial advisory teams, providing actionable milestones to achieve business objectives. At Susan Danzig, we’ve seen that this type of comprehensive plan brings focus, priorities, and real progress to marketing teams. When everyone understands their roles and timelines, teams can move quickly, learn efficiently, and create a substantial impact in client reach and sustainable growth. With a fixed deadline, new managers can swiftly assess the firm’s needs and implement intelligent changes immediately.

1. Unmatched Agility

A 90-day plan helps teams adapt fast in a market that never stands still. With real-time data, teams can identify trends sooner and adjust their financial advisor marketing strategies with less lag. This velocity is crucial when client demands realignment or fresh regulations emerge in financial markets. Teams can trial new concepts, discover what works, and eliminate what doesn’t, all within weeks. Rapid feedback loops allow teams to tweak their effective marketing plans before they fizzle, helping them to stay one step ahead of the competition. If a digital ad-driven campaign isn’t generating leads after two weeks, the team can pivot to webinars or direct outreach without waiting until a quarterly review.

2. Clearer Accountability

Once everyone has assigned tasks and deadlines, things get done on time and with less confusion. With shared dashboards, everyone can easily visualize progress and identify where assistance is required. Metrics such as the number of new leads, event sign-ups, or revenue growth indicate whether each person is accomplishing goals, which is crucial for an effective marketing plan. Monitoring in this fashion creates confidence, allowing financial advisors to own their parts while team leaders can identify gaps swiftly. This makes it easier to level workloads and acknowledge quality work.

3. Sustained Momentum

Short milestones, whether weekly or monthly, help maintain enthusiasm. Little victories accumulate, motivating teams even when larger objectives are more time-consuming. At Susan Danzig, we often remind firms that marketing isn’t a sprint; consistency builds visibility and trust. A 90-day plan helps make social posts, newsletters, or webinars habits, not afterthoughts.

4. Intense Focus

A brief plan compels teams to choose what is important. Rather than pursuing every trend, they focus their efforts on two or three significant initiatives aligned with the firm’s objectives, such as developing a referral marketing program or introducing a new service to attract prospective clients. Teams ideate, pilot, and iterate in a hurry, ensuring every initiative, including the financial advisor marketing plan, receives the focus and support it demands. Obvious criteria for selecting projects, like anticipated impact or fit with customer demand, aid groups in knowing how to decide what to do and what to abandon.

5. Team Alignment

Alignment begins when everyone understands the big picture and where their work fits in. Team meetings, either weekly or bi-weekly, provide opportunities to discuss obstacles, share outcomes, and adjust the effective marketing plan. This open discussion enables teams to help each other and leverage each person’s skill set. When your financial advisor marketing plan aligns with your firm’s strategic goals, every activity has the potential to generate larger victories, such as reducing expenses or increasing revenue by specific percentages. Stakeholders get updates as well, so everyone is aware and can back the plan.

Building Your Team’s Plan

A well-crafted 90-day marketing plan is essential for financial advisory firms seeking to act quickly and stay focused on their goals. At Susan Danzig, we structure these plans to include content calendars, KPIs, and clear timelines with regular check-ins. Teams with these plans often reduce expenses and improve revenue by channeling resources into what truly works.

Define Objectives

Begin by establishing reasonable, easy-to-measure goals within your financial advisor marketing plan. Use the SMART approach, which is specific, measurable, achievable, relevant, and time-bound. Tie these objectives to the company’s broader financial ambitions, such as expanding assets under management or entering new markets. Ensure each team member is aware of these goals, so you’re all working toward the same targets. Check your progress frequently, using actual figures and responses from the market and your team, so you can adjust your marketing strategies if necessary.

Segment Clients

Segment clients by age and their investment needs, focusing on what’s most important to them. Develop customer personas that illustrate a vivid picture of each segment’s goals and pain points, which is crucial for an effective marketing plan. This approach enables teams to prioritize high-value customers with personalized marketing messages that resonate. Refresh these sections as the market evolves or as insights from colleagues in sales and customer success provide new information about prospective clients.

Allocate Resources

Look at what you’ve got: money, people, tools. Allocate more to channels or tactics that deliver, such as webinars or targeted emails. Here’s a simple table that shows how you might split a €10,000 monthly budget:

Initiative

Budget (€)

% Of Budget

Content Marketing

3,500

35%

Social Media Ads

2,000

20%

Email Campaigns

2,500

25%

Events/Webinars

1,500

15%

Analytics Tools

500

5%

Watch your expenses and tweak as you go so that every euro counts!

Select Channels

Choose the channels most relevant to your audience, email for announcements, social media for branding, and content marketing for thought leadership in your financial advisor marketing plan. Experiment with platforms like LinkedIn or WeChat to determine which generates the highest engagement for your financial guidance. Blend channels for greater reach while focusing on effective marketing strategies that work best, cutting out what doesn’t.

The Psychology Of Sprints

The psychology of sprints is crucial for financial advisors, as these short 90-day plans work well by mirroring how teams lose drive and clarity when goals extend too long. By deconstructing large, impersonal objectives into small steps, financial planners can maintain energy and aid teams or individuals in pursuing their financial goals more effectively.

Fostering Urgency

A 90-day deadline provides teams with a definite finish line, much like an effective marketing plan guides financial advisors in achieving their goals. Marketers operate in a sense of now, aware that each day adds to a proximate objective. Deadlines are established and tasks strung together such that there’s no time to drift. Weekly, teams check in to see what’s done and what’s left, ensuring that their financial plan proposals are on track. This makes progress visible and helps keep everyone aligned with their financial aspirations.

They are motivated when members of the team observe their work to be significant. Basic motivators such as praise or minor prizes drive individuals to reach objectives. Teams don’t lose focus because they know each sprint is short. They tackle three top initiatives at a time, which means less distraction and more results, similar to how financial planners prioritize their marketing strategies.

Accountability is baked in. With defined objectives and frequent check-ins, participants have an understanding of what’s due and when. If someone slides, the group can assist or modify swiftly. This results in quick moves and reduced procrastination, much like the need for a robust marketing plan in the financial services industry.

Celebrating Wins

Acknowledgment is a trivial but powerful motivator to sustain teams. When one of the group achieves a milestone, the victory is communal. This can be something as simple as a shout-out in a meeting or a small reward. It keeps morale high and makes people feel seen.

Tales of previous victories are recounted. Teams get tangible evidence that effort pays, and they discover what works. This exchange of best practices allows us all to grow.

A gratitude culture builds trust. They know their insights and endeavors will be appreciated, not overlooked. Teams reflect after each sprint, reviewing what went well and what can be improved next time.

Encouraging Innovation

For teams to grow, they have to try stuff. Leaders create a safe place to share weird or brave things without judgment. Frequent brainstorms give everyone a voice, so fresh strategies surface.

Teams are encouraged to follow trends and acquire new skills. They bring an external perspective or participate in training, which keeps them on their toes. Experimenting with new things isn’t merely permitted, it’s anticipated.

Sprints are a time to test, fail fast, and try again. After each sprint, we pull out lessons and use them to shape the next run, so the process and results keep improving.

Navigating Financial Compliance

Financial advisory groups must develop an effective marketing plan that adheres to compliance standards. Navigating financial compliance requires a 90-day marketing strategy that not only focuses on growth but also on reducing risks and building trust with prospective clients. By implementing thoughtful compliance processes, financial advisors can avoid costly mistakes while ensuring their brand remains credible and resilient.

Proactive Reviews

We recommend teams conduct periodic audits of all marketing collateral. Audits catch errors before they become public and assist advisors in identifying patterns that could lead to risks. Legal and compliance experts should be included in this review cycle, offering oversight and guaranteeing that every campaign complies with the most recent industry standards. Wilmink says that creating a dedicated feedback channel for the team members encourages the real-time reporting of issues, which in turn reduces blind spots.

Recording review results assists with education and workflow enhancement. The results of each review should be recorded and published, aiding teams in avoiding previous mistakes and refining campaigns. This feedback loop helps reinforce compliance and keeps marketing efforts aligned with the firm’s strategy.

Documenting Processes

Explicit, granular records of marketing processes are essential for reliability. All the way from content through distribution, every step should be charted. This includes:

  • Required legal disclaimers for each campaign type
  • Approved templates and branding elements
  • Step-by-step review and approval processes
  • Required sign-offs and responsible parties
  • Change logs for version control
  • Storage location for final materials

A centralized repository makes it easy to track down and update essential documents. Periodic reviews keep these records up to date with the latest regulations and internal shifts. This simplifies navigation and welcomes new members as they come aboard.

Standardizing Messaging

A common messaging architecture guarantees that each message exhibits the firm’s values and satisfies compliance requirements. Language, tone, and visual style guidelines mitigate against potential compliance missteps and enhance brand recognition. Training sessions help team members internalize those rules and put them into practice.

Monthly messaging reviews ensure teams keep messages fresh and client-focused. It’s particularly crucial as financial advisors handle expanding digital presences and intensified oversight.

Corporate Training for Financial Advisory Firms

Measuring What Matters

Financial advisory teams must measure the right metrics to ensure their effective marketing efforts are yielding results. This approach encourages teams to take actionable steps and evaluate what truly matters for sustainable growth. By leveraging digital tools like CRM platforms and analytics dashboards, financial advisors can observe real-time outcomes and pivot quickly. Weekly data analysis, focusing on specific campaigns while establishing benchmarks, keeps teams aligned and accountable. By monitoring successful marketing strategies, companies can invest smarter and connect with more prospective clients. Here is what really counts.

Lead Velocity

Metric

Last 90 Days

Previous 90 Days

Change (%)

Lead Velocity

15/month

9/month

+66.7%

Conversion Rate (%)

17/month

13/month

30.8%

Teams need to understand where leads originate. Digital campaigns, events, and referrals all generate different outcomes. Looking at these sources reveals what fuels the highest-quality leads, not just the greatest number. If leads from one channel convert better, that’s where to concentrate. Teams establish lead velocity targets for every 90-day cycle and then examine weekly metrics to observe advancement. Applying lead velocity like this results in less guesswork and more predictable growth.

Client Acquisition

Tracking new clients per quarter indicates if campaigns are targeting the appropriate customers. Teams monitor acquisition costs per campaign, ensuring monies go where they perform best. If an approach brings in new clients for half the cost, then it makes sense to move the budget there next cycle.

Getting customer feedback helps focus marketing copy. Indirect feedback from surveys or calls can indicate why certain initiatives succeed. Focused campaigns constructed on these insights convert more prospects into customers. Structured-plan advisers get significantly more leads, 168% more than those without, demonstrating the power of deliberate, continuous measurement.

Engagement Rates

Teams track engagement rates, including email opens, event sign-ups, and social clicks, on all channels. Comparing these numbers with earlier benchmarks shows whether content connects. Testing, whether it’s a simple A/B test, like trying two subject lines, or something more complicated, makes it easy to see what works.

Weekly reviews keep the team agile. If a post gets twice the clicks, your next plan can use that style. Clear benchmarks for engagement force the team to keep stretching, not just regurgitate last quarter’s work.

Team Contribution

No individual input can make a plan powerful. Teams measure who generates leads, who closes deals, and who keeps customers delighted. Performance reviews conducted every quarter reveal where everyone excels. Acknowledging these victories keeps individuals engaged.

Sharing insights in meetings creates camaraderie. Open conversations about what’s working make us all improve. Team goals for the quarter keep everyone on the same page and ensure the entire group moves in the same direction.

Avoiding Common Pitfalls

Financial advisory firms’ marketing is plagued by common pitfalls, including weak planning, unclear team roles, and poor tracking of goals. These obstacles can impede expansion, incite disputes, and muddy the company’s direction. A 90-day team-level financial advisor marketing plan helps break these big issues into smaller, easier-to-manage tasks. Looking over team organization and conducting a SWOT analysis once a year allows companies to reflect on their strengths, identify vulnerabilities, and strategize for expansion. Without it, teams can maintain bad habits, overlook emerging trends, or not respond to market changes.

A typical mistake is a lack of vision. This misaligns teams working on different pieces, creates confusion, and can jam momentum. When the team fails to align on goals and values, projects can become scatterbrained resource wasters. Companies need to ensure that every member understands what the collective is trying to accomplish and where their efforts fit in. Establish responsibilities for everyone, particularly after team shifts, to prevent tasks from being duplicated and to ensure that nothing falls through the cracks.

Historical marketing campaigns are the key. They demonstrate what succeeded and what did not, preventing teams from repeating the same errors. If a social media push didn’t bring customers through the door, go over the steps, the messages, and the timing. Use these lessons to adjust to the next campaign. Metrics are crucial in this; they measure if team objectives are achieved and highlight where improvements can be made. An effective marketing strategy is essential for tracking these metrics.

Teamwork and open talk are equally important. Utilizing tech solutions such as CRM software allows teams to document important information, monitor activities, and engage in lead follow-up. It eliminates wasted opportunities and keeps everyone on the same page. When troubles arise, discuss them early. That way, minor issues do not blossom into expensive ones. A robust marketing plan can also support this collaboration.

Plans change quickly, so it’s smart to have contingency plans for your bold marketing maneuvers. If an outreach plan doesn’t land, there better be a fallback prepared to keep things moving. Check pay plans frequently to ensure they remain equitable and connected to individual contributions.

Final Remarks

At Susan Danzig, we know why financial advisory firms need a 90-day marketing plan at the team level. These short, focused blocks give teams the clarity to identify successes and gaps quickly. They collaborate, share insights, and use feedback to refine their next moves. Testing what works keeps the plan practical and on track.

With a 90-day plan, teams stay sharp, remain compliant, and track metrics that show real results, no guesswork, just measurable growth. If you want to make an impact, begin with focus and decide what you want to accomplish over the next 90 days. Experiment, build on what succeeds, and communicate often.

It’s time to see what a 90-day plan can do for your team, partner with Susan Danzig, and start achieving real, focused growth today.

Frequently Asked Questions

1. Why Is A 90-Day Marketing Plan Important For Financial Advisory Teams?

A 90-day plan helps financial advisors focus on clear, short-term goals. It builds accountability, enables rapid course correction, and facilitates progress monitoring. This effective marketing strategy keeps teams aligned and responsive in a fast-changing financial services landscape.

2. How Does A Team-Level Marketing Plan Improve Results?

A team-level plan guarantees that you’re all working toward common goals, which is essential for a successful marketing strategy. It brings clarity to roles and priorities, driving more effective collaboration and results for financial advisors.

3. What Is The Benefit Of Using A 90-Day Sprint In Marketing?

These 90-day sprints decompose big goals into small, actionable tasks, allowing financial advisors to enhance their marketing strategies effectively. This makes success easier to measure and keeps motivation high as teams adjust their marketing efforts regularly.

4. How Can Financial Advisory Firms Stay Compliant While Marketing?

Firms must adhere to local and global financial regulations, and an effective marketing plan can enhance client trust. A 90-day plan aids in scheduling compliance checks, minimizing errors while instilling confidence in prospective clients.

5. What Should Financial Teams Measure In A 90-Day Marketing Plan?

Lead generation, client engagement, and ROI are key metrics for financial advisors. Teams should monitor progress weekly and adapt their marketing strategies according to results, ensuring time and resources are spent wisely.

Take The First Step Toward Smarter, Faster Growth

Your team doesn’t need another long, stagnant marketing plan that collects dust; it needs direction, accountability, and momentum. At Susan Danzig, we specialize in helping financial advisory firms like yours clarify their message, strengthen team performance, and design 90-day marketing strategies that actually move the needle. Whether you’re looking to align your advisors under one cohesive brand or sharpen your client acquisition process, we’ll help you identify your next right step for measurable success.

Ready to see what a focused strategy can do for your firm? Book your Strategy Session today, or take our quick quiz to find out how aligned your team’s marketing efforts are right now. Your next 90 days of growth start here.

How To Align Individual Advisor Brands With Firm-Level Strategy

At Susan Danzig, we help firms and advisors align their individual brands to fit the larger strategy of the organization. Advisors have their own client groups but still need to reflect the values, mission, and voice of the firm in their work. When everyone moves in the same direction, the firm can build trust, maintain a clear message, and provide a consistent client experience. Many firms establish basic guardrails, weekly team discussions, and candid feedback to assist with this. The following paragraphs illuminate simple tactics and resources that assist advisors in remaining faithful to their personal brand while supporting the firm’s objectives at every opportunity.

Key Takeaways

  • Achieving effective alignment between individual advisor brands and the broader firm strategy requires a structured approach that balances personal authenticity with organizational consistency.
  • By defining clear brand guidelines and a flexible framework, advisors can be inspired to communicate their unique strengths in a way that connects seamlessly with the firm’s mission and visual identity.
  • Co-creating values and mapping advisor expertise increases engagement while enabling marketing to customize offerings to client needs across diverse markets.
  • By offering toolkits, mentorship, and training, advisors are empowered to develop real personal brands that connect with local and global audiences.
  • Ongoing tracking of messaging, client input, and advisor involvement maintains momentum and brand integrity.
  • By measuring brand consistency and celebrating successes, you’re creating a culture that supports individual growth and firm-level goals.
Corporate Training for Financial Advisory Firms

The Brand Duality Dilemma

The brand duality dilemma refers to the tension between advisor self-branding and a firm’s shared voice, impacting the overall business strategy. This is a problem not of appearance or logos but of authentic identity, both internal and external. When these don’t align, ambiguity multiplies and consumers abandon faith. Studies demonstrate that businesses that focus on strategic alignment and fix this issue, where each advisor’s voice aligns with the firm’s essence, experience increased sales and dedicated customers. Too much sameness can strangle creativity, while too much freedom threatens chaos. Employee alignment is key because advisors are the primary face that clients encounter. Leaders need to set the tone, ensuring the narrative within aligns with what is communicated externally. The McKinsey 7-S model may assist as it outlines ways to maintain systems, style, and staff in sync. Getting this balance wrong can cost real money, with misaligned brands losing as much as 7% of revenues. The path ahead involves a close examination of culture, values, and communication.

Individual Vs. Collective

Personal brands enable advisors to distinguish themselves by showcasing their expertise, approach, and narrative to prospective clients, key aspects of effective business strategies. The company’s brand not only unites but also inspires confidence at a more macro level, aligning with organizational goals. Advisors must honor what makes them unique, ensuring their actions serve the firm’s specific goals. This can be challenging, but a firm can support this by establishing clear policies that outline what’s permitted while allowing each advisor’s flair.

At Susan Danzig, we’ve seen that when advisors engage in strategic partnerships, they exchange advice, build trust, and strengthen the entire team. For example, implementing monthly team sessions to discuss brand successes and challenges aids in education and consistency. Policies might include checklists for digital posts or guidelines for leveraging corporate logos, ensuring everyone stays on target.

Authenticity Vs. Uniformity

Standard

Authenticity Example

Uniformity Example

Tone of Voice

Advisor shares personal story

All use the same scripted pitch

Visual Elements

Custom photos from real client events

Stock images for all profiles

Messaging Content

Local client success story

Generic global market update

A company can dictate the stuff advisors communicate, but allow them to control the angle. That is, allowing advisors to discuss what is important to them, in their own language, inside the broader message the firm represents.

If advisors feel free to be themselves, they’re more likely to speak up and share new ideas. Leaders should review what gets posted or said, ensuring that both the firm’s core values and each advisor’s voice shine through. This keeps the brand authentic and prevents it from seeming phony or contrived.

Freedom Vs. Framework

Advisors require clear boundaries. An agency can define the non-negotiables, such as always including the brand logo or using pre-approved messaging, and let consultants decide how to tell their stories within those boundaries.

A loose, flexible schedule allows advisors to experiment and still keeps the brand focused. For example, advisors could experiment with new methods of engaging clients online as long as they adhere to core brand messaging and principles.

With explicit guidelines, consultants can ideate, prototype, and publish new concepts. This not only makes their work more fun, but also injects the entire brand with new life. When all knows the dance steps and is trusted to move within them, the brand remains powerful and the group feels appreciated.

Define Your Brand Architecture

Brand architecture is the skeleton of how a firm’s brand translates to its advisors and clients, playing a crucial role in achieving strategic alignment with organizational goals. It establishes the structure of brands, sub-brands, and brand relationships. Three main models shape this structure: the branded house, where a single master brand covers all products, the house of brands, where each product or service stands under its own unique brand, and the hybrid model, which blends elements of both approaches. Choosing the right model depends on business goals, services, and the target audience. A well-defined brand architecture reduces confusion, facilitates expansion, and enables a company to leverage the strength of its parent brand to accelerate credibility for new products or services.

Firm’s Core Strategy

The firm’s business strategy serves as the foundation for all branding efforts. It is crucial to be explicit about the long-term mission and vision, whether striving to be the leader in innovation, service, or community building. These aspirations guide the brand positioning and align with the firm’s strategic goals. When a firm opts for a branded house, each advisor operates under the same promise and values, ensuring that the underlying narrative about the firm remains consistent.

Every brand message, from the website to customer pitches, must resonate with the same strategic objectives, matching the look, language, and behavior to the firm’s distinctive value. This includes qualities like transparency, dependability, or personalized counsel, which are essential for effective strategic partnerships. Reliable communication fosters trust with clients and internal teams alike. For instance, if a firm emphasizes digital innovation, each advisor’s collateral should reflect this focus through tech-powered tools or digitally-oriented service channels.

Advisor’s Personal DNA

Every advisor has their own strengths, experiences, and style. Finding these characteristics is crucial in constructing personal brands that still fall within the realm of the firm’s strategy. Advisors should be assisted in plotting their own brand narratives, client approach, expertise, values, and more. A strong narrative could emphasize an advisor’s experience in international markets or a commitment to impact investing.

Personal brands shouldn’t be at odds with the firm’s goals but rather complement them. If the firm’s vision is about empowering clients, advisors can demonstrate how their specialized training makes this possible. The firm should empower advisors to use their voice but stay on message, helping them craft stories that feel real and resonate with clients across cultures and backgrounds.

The Non-Negotiables

A powerful brand requires guidelines that make it uniform across all consultants. These non-negotiables are the have-to-haves that never shift, regardless of the advisor’s approach or pedigree. They range from logo usage to color palettes, tone of voice, messaging pillars, and client promises. For instance, all advisors would have to use the firm’s primary colors and logo placement on any client-facing document. Key messages such as “client-first service” or “global reach” need to appear in each advisor’s pitch.

Create a checklist:

  • Use approved logos and colors in all materials.
  • Follow the set tone and key messages.
  • Share the firm’s core promise in every client interaction.
  • Stick to agreed visual standards for presentations or reports.
  • Keep to compliance and ethical guidelines.

Every advisor should get crisp training on these basics and know where to turn for resources if uncertain. The firm should verify alignment regularly, providing assistance where needed to maintain focus.

Corporate Training for Financial Advisory Firms

Create Your Alignment Blueprint

Powerful alignment blueprints connect advisor brands to the firm’s fundamental business strategy. It begins with a sanity check of the status quo, using models such as 7-S to identify what holds and what falls apart.

At Susan Danzig, we guide firms through co-creating values, mapping expertise, defining guardrails, building toolkits, and launching internal brand programs that drive measurable consistency. Our approach ensures the strategic goals blueprint isn’t just a document; it becomes a living component of the firm’s culture.

1. Co-Create Values

Include advisors in the shared values setting process as part of your strategic alignment efforts. Their stake matters for genuine investment. Conduct workshops or small group sessions to gather their input. When advisors help shape values, they feel invested and are more likely to live them out. These co-created values should manifest in all branding pieces and daily work, not just on paper. Updating your materials with real examples makes the brand authentic and supports effective business strategies that help everyone pull in the same direction.

2. Map Expertise

Begin by writing down what unique skills and knowledge each advisor brings to the organization. Draw up charts or simple visual maps so clients and team members can see this at a glance. This not only assists in pairing the appropriate advisor to client demands but also enables marketing strategies to emphasize actual capabilities rather than generic buzzwords. Mapping expertise simplifies measuring strategic alignment and identifying gaps requiring additional training or hiring. As client expectations shift, refresh these maps to keep them relevant and useful.

3. Define Guardrails

Defining branding guidelines is essential for ensuring that every advisor aligns with the firm’s style and voice, which is a critical aspect of effective business strategies. Providing examples of on-brand and off-brand elements, such as sample social posts and pitch decks, illustrates the importance of maintaining brand consistency. By connecting these rules to the strategic goals outlined in the blueprint, advisors can adapt to market changes while retaining their core values and enhancing organizational performance.

4. Build Toolkits

The Build Your Brand Basics Toolkit includes email, presentation, and social post templates, essential for effective business strategies. By adding best practice guides and transparent step-by-step instructions, you can ensure that your leadership team conducts brief training, enabling consultants to understand how to utilize these resources in actual projects effectively.

5. Launch Internally

Unveil your strategic alignment blueprint with a targeted soft launch to the inside using short talks and slides. Keep the process open, allowing advisors to inquire and provide comments. Establish check-ins and updates, group chats, or newsletters to inform everyone. This step ensures the strategic goals blueprint is not just a document but a living component of the firm’s culture.

Unify Your Narrative

To unify your narrative is to ensure that each advisor’s tale aligns with the firm’s main theme and supports the overall marketing plan. This builds trust and credibility by presenting clients with a compelling, coherent story that reflects your strategic goals. When the message is muddled or off course, clients can get lost or lose confidence. This is done through purpose, values, and what makes your firm special, making strategic alignment essential for clarity and resonance.

Shared Language

Building a common language begins by establishing terms that tie to the firm’s mission, vision, and values, aligning with the overall marketing plan. This language should be simple to apply in daily conversations, emails, and social media updates to ensure effective business strategies. Training sessions can help advisors learn this language and practice using it with each other, fostering strategic partnerships. Have advisors exchange concepts and anecdotes, making the words automatic. Watch client communications to see if the language is consistent with the brand positioning. Small group feedback or peer reviews can plug holes.

Consistent Messaging

Establishing easy, yet explicit boundaries around what advisors should be saying and how they should be saying it is crucial for maintaining effective business strategies. Create sample emails, social media posts, and presentations that align with the company’s mission and strategic goals. Advisors should refer to these guides to maintain a consistent message in person, on the phone, or online. Always vet marketing content to keep tone and facts consistent. Providing feedback straight to advisors who are doing things that work and need to change is part of the strategic planning process. Getting everyone on the same page prevents conflicting impressions and cultivates a professional image.

Client-Centric Stories

Instead, advisors should share authentic, real-world stories demonstrating how they assist clients in achieving their objectives. These stories humanize the brand and demonstrate a tangible effect while creating an emotional connection. Combine Your Story

Feature client testimonials or case studies in brochures and posts, using plain language that reflects the firm’s voice. Maintain a story library that any advisor can tap into. This keeps stories fresh and avoids using the same example repeatedly. Publishing these stories helps both new and experienced advisors see what works and keeps the brand’s mission front and center.

Empower Advisor Authenticity

The key to aligning individual advisor brands with firm-level strategy is creating room for authenticity while maintaining a shared vision. Advisors who reveal their true personalities and beliefs foster greater connection and trust with clients. In a digital-first world, a powerful personal brand is not a nice-to-have; it is essential. Advisors must demonstrate subject matter expertise, relate as human beings, and align with the broader narrative the firm wants to convey.

Below are steps and initiatives for empowering advisor authenticity:

  1. Launch mentorship programs pairing experienced advisors with newer ones.
  2. Give advisors freedom to pick content topics and formats.
  3. Provide technology stacks that help advisors show their expertise.
  4. Track progress and gather feedback to measure these initiatives.

Mentorship Programs

Mentorship is core to empowering advisors to develop their brands in sync with the firm. By pairing veteran advisors with rookies, you can share best practices, industry subtleties, and branding tactics. Mentors can teach mentees how to define a niche, select their values, and display their strengths in an authentic way that aligns with the firm’s brand. Mentorship gives them a safe space for feedback, so advisors can adjust their message and learn from missteps.

Mentorship success tracking is pivotal. Leverage regular check-ins, straightforward metrics, and feedback loops to ensure that partnerships are functioning and objectives are fulfilled. This facilitates identifying what makes advisors exceptional and how to better them.

Content Freedom

Advisors should have space to mold content that suits their expertise and personality. Letting them select topics, be it sustainable investing, retirement planning, or other specialties, lets them display a defined niche. Clients resonate more with advisors who resonate with themselves. That’s why 7 in 10 of us choose brands that mirror our values.

Assistance is provided in training in blogs, micro videos, or social posts, so advisors feel empowered and adept. Content checking for a style consistent with the firm’s overall keeps things on track. Personalization and differentiation make advisors memorable, and memorable advisors get referrals because clients want to share a brand they get and trust.

Technology Stacks

Equip advisors with digital tools. Provide access to website builders, CRM, and analytics dashboards. A strong digital presence is typically your client’s initial point of contact, and it takes them just 50 milliseconds to decide on a first impression. Empower Your Advisor Authenticity.

Continued coaching makes sure advisors wield these tools effectively. Tech should empower both the advisor’s authenticity and the firm’s strategy. Regular stack reviews, with advisor input, keep solutions fresh and relevant. Authentic digital branding, supported by the right tech, enables advisors to win trust and forge enduring client connections.

Measure Alignment Impact

When firm-level strategy and individual advisor brands swim in the same direction, firms experience greater impact. Research indicates that as much as 80% of the performance variance between organizations can be attributed to strategic alignment. This alignment, along with team buy-in, accounts for nearly 90% of the gap in operational results. Companies that focus on measuring strategic alignment gain clearer insights and can adjust quickly when things shift. With metrics, client feedback, advisor engagement data, and brand consistency checks, leaders see what’s working and where to improve.

The Client Feedback

  • Send online surveys after meetings to collect feedback on advisor branding.
  • Arrange a focused client reading of Measure Alignment Impact
  • Employ anonymous suggestion boxes, online and offline, to solicit honest answers.
  • Track social media and third-party review sites for spontaneous feedback.
  • Conduct client focus groups to discuss brand and service perception.

Survey data helps you spot trends, while measuring strategic alignment through interviews reveals if clients perceive advisors as authentic embodiments of the firm’s culture. Over time, comparing feedback uncovers whether brand positioning aligns with client needs or if it misses the mark, aiding in effective business strategies and impactful branding. 

Advisor Engagement

Record how frequently advisors attend branding workshops, access firm resources, or participate in team check-ins. The more engaged they are, the more effective business strategies they develop. Teams with regular one-on-one check-ins report higher alignment scores, illustrating the importance of ongoing dialogue. By comparing advisor participation between regions and teams with a zero to one hundred alignment score, this data emphasizes areas of weakness and guides training where it is most necessary. It is through advisors sharing their branding stories that they help others, gain trust, and spark ideas, ultimately fostering a community of collaborative achievement.

Brand Consistency

Review all client-facing materials, e-mails, presentations, and digital profiles at regular intervals to identify off-brand messaging. Sample advisor communications at random, looking for strategic alignment with firm standards. Regular training helps advisers keep those brand rules front-of-mind, particularly as the business strategy evolves. Cheer on teams who maintain effective business strategies and make those wins visible to all. Frequent check-ins, gap analysis, and rapid realignment ensure the entire organization stays aligned with the company’s strategic goals. By emphasizing team behavior, cultural fit, and outcomes, companies measure strategic alignment impact to ensure brand alignment generates tangible business results. Projects with high alignment are 57% more likely to meet their objectives.

Final Remarks

At Susan Danzig, we believe powerful firm brands develop when every advisor remains authentic to their own unique voice yet embraces the firm’s overarching narrative. Both sides work well together when there are clear goals and simple plans. Establish guidelines for what the brand conversation looks and sounds like. Check often to see if this brand mix works in real life. Let advisors talk in their own voice, but provide them with the tools to stay on point. A tight brand story resonates as authentic and attracts clients who desire trustworthiness and expertise. Keep it real, keep it clean, and keep checking your progress. Contribute your own brand style tips and stories. Participate in the conversation, contribute to a blueprint everyone can follow, and influence the brand universe for everyone.

Frequently Asked Questions

1. What Is The Main Challenge In Aligning Advisor Brands With Firm-Level Strategy?

The trick is harmonizing personal advisor brands with the overall business strategy. Both need to remain in strategic alignment to instill confidence and prevent client frustration.

2. Why Is Defining Brand Architecture Important For Alignment?

This architecture aids in measuring strategic alignment by providing clarity on the roles and relationships between individual and firm brands, helping to avoid duplication or tension and laying a good basis for unified messaging.

3. How Can Firms Create An Effective Alignment Blueprint?

Firms should have a strategic plan that involves explicit direction, messaging, and continuous feedback to ensure advisor and firm brands complement one another.

4. What Does It Mean To Unify Your Narrative?

Unifying the story involves ensuring that all messaging from the firm and individual advisors aligns with the strategic goals and objectives, fostering consistent branding that builds client confidence.

5. How Can Advisors Maintain Authenticity While Aligning With The Firm Brand?

Advisors can weave in personal stories and expertise while adhering to firm guidelines, fostering strategic partnerships with clients. This lets them engage clients as individuals and advocate for the firm’s strategic goals and business strategy.

Schedule A Team Assessment Today

Is your advisory team fully aligned behind one clear, powerful brand message? At Susan Danzig, we help firms uncover where alignment succeeds and where it slips, so that every advisor’s individual brand supports the firm’s overall strategy. Our Team Brand Alignment Assessment identifies strengths, opportunities, and actionable next steps to unify your firm’s vision, voice, and values. Whether you’re refining your brand architecture, defining advisor guardrails, or improving client messaging, we’ll help you turn clarity into measurable growth.

Ready to see how your team measures up? Schedule your assessment today and discover how authentic alignment can strengthen your brand, build trust, and boost performance across your entire organization.

Categories

Authors

  • Susan Danzig (409)
  • FAST Track Your Business

    Discover the 7 steps to attract your ideal clients and grow your book of business.